 Follow Us on Google Discover
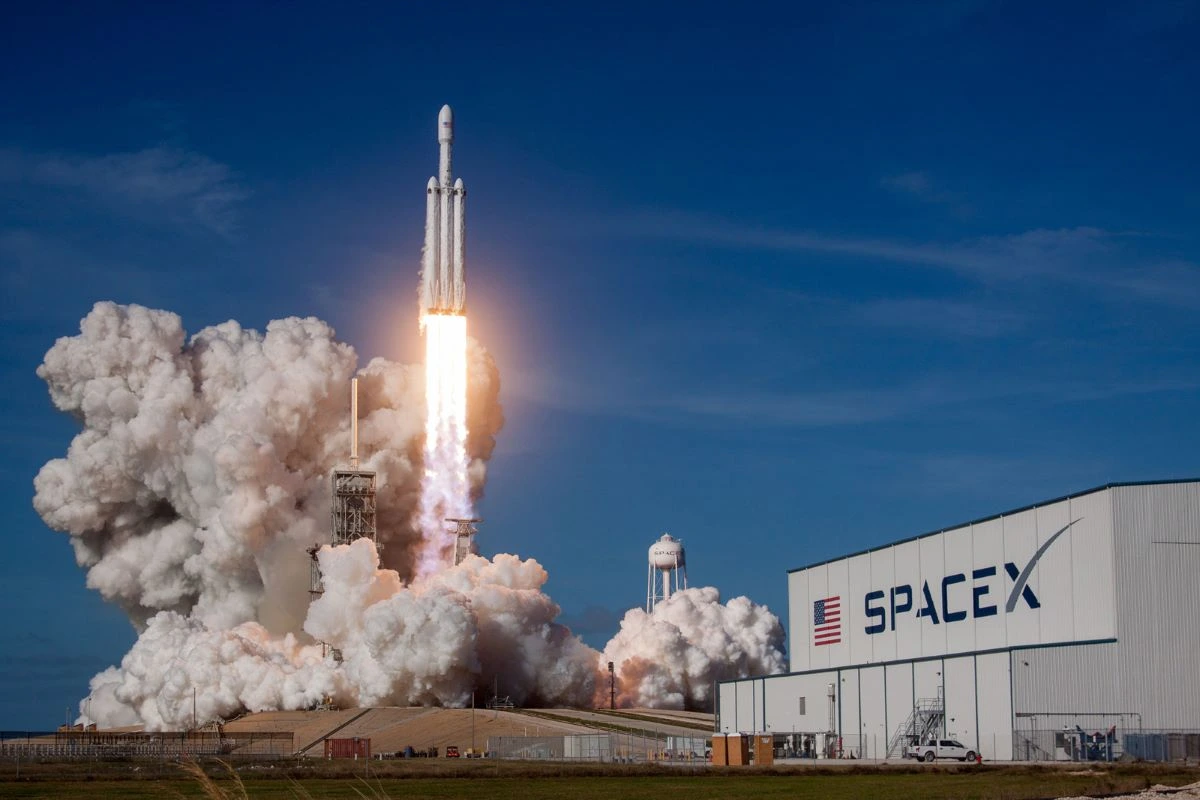
SpaceX reported a 161% year-on-year increase in third-quarter revenue to $14.58 billion on Tuesday, up from $5.58 billion in the same period of 2025, beating analysts’ estimates as growth in its artificial intelligence (AI) business and Starlink satellite internet unit boosted performance.
The company’s revenue for the three months ended September 30, 2026, exceeded analysts’ estimate of $12.72 billion, according to data compiled by LSEG.
SpaceX also reported a net profit of $4.4 billion, compared with analysts’ expected profit of $1.57 billion.
The result marked a turnaround from the second quarter, when the company recorded a net loss of $541 million on revenue of $7.81 billion.
Also Read
AI business and Starlink drive growth
SpaceX’s AI business has become a major source of revenue for the company, supporting founder Elon Musk’s broader ambitions in artificial intelligence and space-based computing.
The company generates much of its AI revenue by renting out data-centre capacity to developers and technology companies, including Anthropic, Google and Reflection AI, rather than relying primarily on its own AI models.
- Its AI operations span Grok, the chatbot developed by xAI, the social media platform X and a growing data-centre business. However, SpaceX’s own AI software has so far been overshadowed by competitors such as OpenAI, Anthropic and Google.
- The AI business is also the company’s largest area of investment. SpaceX has reported large operating losses in the unit and cautioned that sustained investment will be needed before it can consistently generate profits.
- Starlink and SpaceX’s broader connectivity operations have been key financial drivers, with the satellite internet unit continuing to expand its subscriber base through additional satellite launches and a growing range of consumer, enterprise, aviation, maritime and government services.
- However, SpaceX has warned that expanding into markets beyond wealthier countries could reduce average revenue per user over time. Investors are watching whether lower-priced plans and international expansion will put pressure on revenue per subscriber.
The company is also spending heavily on network coverage, capacity and direct-to-device mobile services as it seeks to expand its reach while improving the economics of its satellite network.
Starship development adds to investment costs
Beyond its AI and connectivity businesses, SpaceX continues to invest in commercial launches, government missions and the development of Starship, its next-generation reusable rocket system.
- Starship has yet to enter commercial service but is expected to support the deployment of higher-bandwidth Starlink satellites and potentially enable orbital AI-computing infrastructure. The company’s ability to develop a reliably reusable launch vehicle remains central to its longer-term strategy.
- SpaceX’s space segment includes commercial launches, government missions and Starship development, making it a significant source of costs and uncertainty.
Falcon launch activity has remained robust, although revenue can vary depending on the mix of internal Starlink deployments, commercial customer missions and government contracts.
SpaceX has increasingly prioritised launches for its own satellite network over third-party payloads while absorbing significant costs associated with Starship’s development.
SpaceX’s corporate milestones
SpaceX’s latest results follow major developments in its corporate structure and satellite internet business.
In February 2026, Nairametrics reported that SpaceX merged with Musk’s AI company, xAI, in a deal valued at $1.25 trillion, bringing its rocket, satellite internet and AI operations under one corporate structure.
Starlink reached 9 million global customers in December 2025, reflecting the scale of its satellite internet business as SpaceX continues to expand its connectivity services.
SpaceX also secured a reported $30 billion computing agreement with Google, underscoring the scale of its planned AI infrastructure business.