 Follow Us on Google Discover
The dominance of banks among Nigeria’s most valuable and best-performing listed companies is a sign of deeper structural weaknesses in the economy rather than evidence of economic strength.
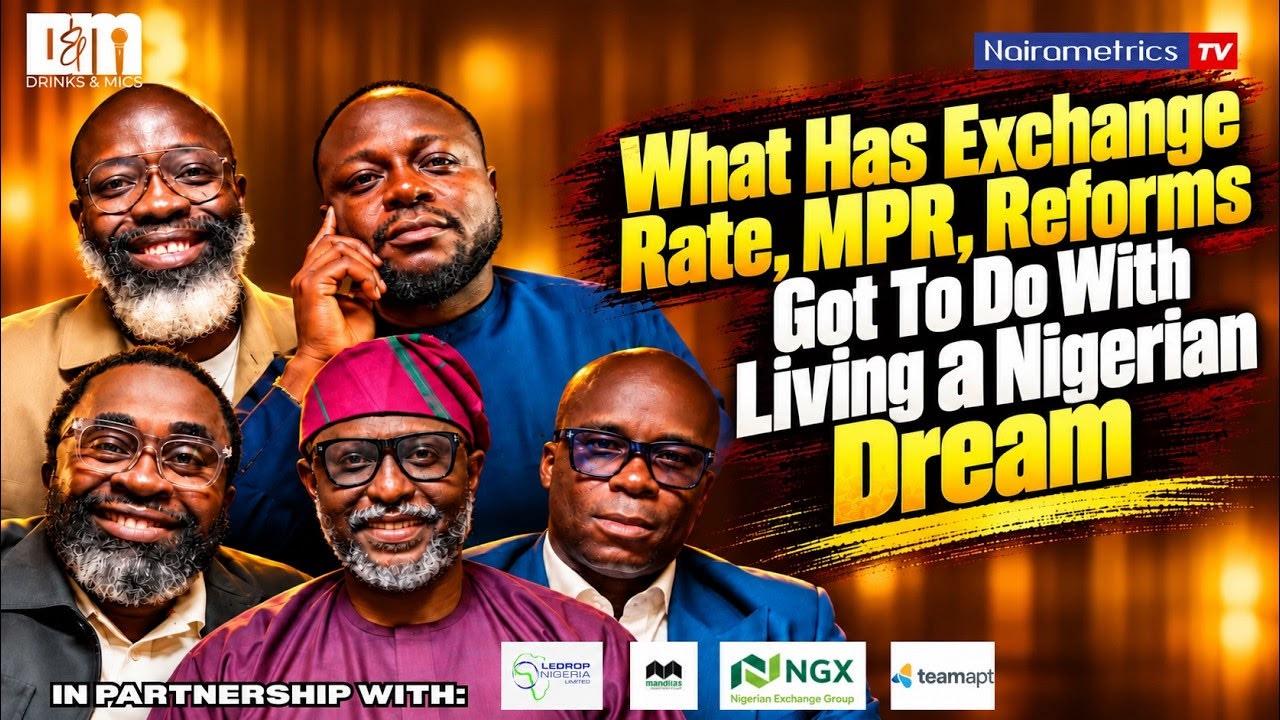
This is according to business leaders Oluwatobi Joshua Ajayi, Founder and Chief Executive Officer of Nord Automobile Limited; and Olukayode Olusanya, Founder of Oak Holdings.
The duo made the remarks during a recent episode of the Drinks and Mics podcast hosted by Ugodre Obi-Chukwu, where they argued that productive sectors such as manufacturing, agriculture and real estate should be driving economic value creation and stock market performance.
Their comments come amid a strong rally in banking stocks, which have added more than N11 trillion in market value so far in 2026.
‘A sign of an economy that is not working well’
Ajayi, Founder and Chief Executive Officer of Nord Automobile Limited, said the continued dominance of banks on the Nigerian Exchange reflects an imbalance in the economy.
- “The most successful companies on our stock exchange are our banks. To me, that’s a sign of an economy that is not working well. It’s not.”
According to him, sectors directly involved in production and value creation should be occupying the top ranks of Nigeria’s capital market.
- “You should have your hard, boring sectors — agriculture, real estate, manufacturing. Those are the people that should be leading your top 20, not your banks. The banks are supposed to facilitate the growth.”
Ajayi argued that banks should primarily serve as enablers of economic activity rather than being the dominant beneficiaries of it.
Calls for restructuring financial flows
Echoing the concerns, Olukayode Olusanya, Founder of Oak Holdings, said Nigeria needs to rethink how capital flows through the economy.
- “The earlier we start restructuring our finance flows in this country, the better for everyone. Otherwise, we are just on a wild goose chase.”
Responding to questions on what such restructuring would entail, Olusanya pointed to the banking sector recapitalisation exercise and recent foreign capital inflows as reasons lending rates should be easing rather than remaining elevated.
- “You’ve asked banks to recapitalize. A lot of FDIs has hit our economy, there’s a lot of liquidity, such that there should be no excuse on why your loans and your lending rates should increase, especially to the real sector, manufacturing.”
‘The problem is the regulator’
When Obi-Chukwu noted that banks also contend with their own funding and operating costs, Ajayi directed responsibility toward the Central Bank of Nigeria (CBN).
- “No, no, no. I think the reason is this. And I think the problem is the regulator, which is CBN.”
Olusanya further argued that the structure of Nigeria’s banking system is geared toward short-term commercial transactions rather than long-term productive investments.
- “This current banking system we have is more of a short-term, very short-circle, trader system. You sell groundnut, buy, return my money, buy. It’s not designed for real estate, for example, where you want to borrow to build.”
According to him, the financing model creates significant challenges for sectors that require patient capital and long investment horizons.
- “Before your foundation work starts, somebody’s already asking for his money back with interest. It’s not designed for any long-term thing.”
Banking stocks outperform broader market
The comments come against the backdrop of a remarkable rally in Nigerian banking stocks in 2026.
Data reviewed by Nairametrics shows that the NGX Banking Index gained 67.96% year-to-date as of September 14, outperforming the broader NGX All-Share Index, which returned 56.35% during the same period.
The rally increased the combined market capitalisation of 12 listed banks tracked by Nairametrics from N16.44 trillion at the end of December 2025 to N27.61 trillion by September 14, 2026.
This represents a gain of approximately N11.17 trillion in less than nine months.
More insights
While banking stocks have delivered some of the strongest returns on the Nigerian Exchange this year, analysts note that many lenders still trade at relatively modest valuations compared with peers across Africa.
Several banks continue to trade below book value, while others command lower earnings multiples than comparable institutions in Kenya, South Africa, Ghana and Tanzania.
However, the concerns raised by Ajayi and Olusanya go beyond market valuations. Their argument is that a healthy economy should see stronger representation from productive sectors that create goods, jobs and industrial capacity, with banks playing a supporting role in financing that growth rather than dominating the list of the country’s most successful companies.