 Follow Us on Google Discover
As regulatory scrutiny of cross-border financial services increases, payment companies operating across multiple jurisdictions face a second challenge alongside building faster technology: securing the regulatory coverage needed to move money compliantly across markets.
For African businesses managing cross-border trade, relying on unverified routing channels poses severe operational and balance-sheet risks. Transactions moving through opaque correspondent banking chains face persistent threats of being flagged, frozen, or delayed during intermediary compliance checks.
Building direct regulatory alignments across jurisdictions addresses this systemic risk at its root. Oneremit’s compliance framework integrates robust regulatory oversight mechanisms, strengthening the financial infrastructure behind its core mission to help African businesses transact globally within established regulatory frameworks.
Also Read
The company operates under four regulatory frameworks across major North American and African trade corridors—including IMTO licensing in Nigeria, FINTRAC and RPAA registrations in Canada, and FinCEN compliance in the US—with additional regulatory expansion underway in the UK, Côte d’Ivoire, and Ghana.
This multi-jurisdictional regulatory foundation ensures outbound enterprise transfers move through fully audited, legal channels. By operating within strict Anti-Money Laundering (AML) and Know-Your-Business (KYB) parameters, the platform offers corporate clients the institutional trust required to manage large-scale capital flows.
Building Beyond a Single Payment Corridor
Oneremit’s operational model enables African enterprises to settle international obligations directly in local currency, while the company handles the currency conversion, routing, and payment delivery required to reach beneficiaries in supported markets.
The company’s regulatory expansion reflects a deliberate strategy to build beyond single-corridor remittance paths, as each new market can introduce separate regulatory, compliance, banking and operational requirements.
Canada’s RPAA framework, for instance, requires payment service providers to register with the Bank of Canada and comply with stringent operational risk management, incident response guidelines, and end-user fund safeguarding requirements. Registered entities remain subject to the Bank of Canada’s direct supervision and enforcement standards.
Similarly, the Central Bank of Nigeria’s IMTO framework strictly governs international money transfer operations, setting rigorous benchmarks for corporate governance, compliance, and permissible financial activities.
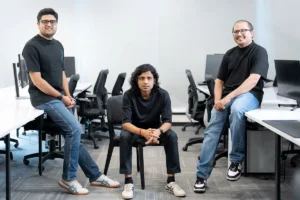
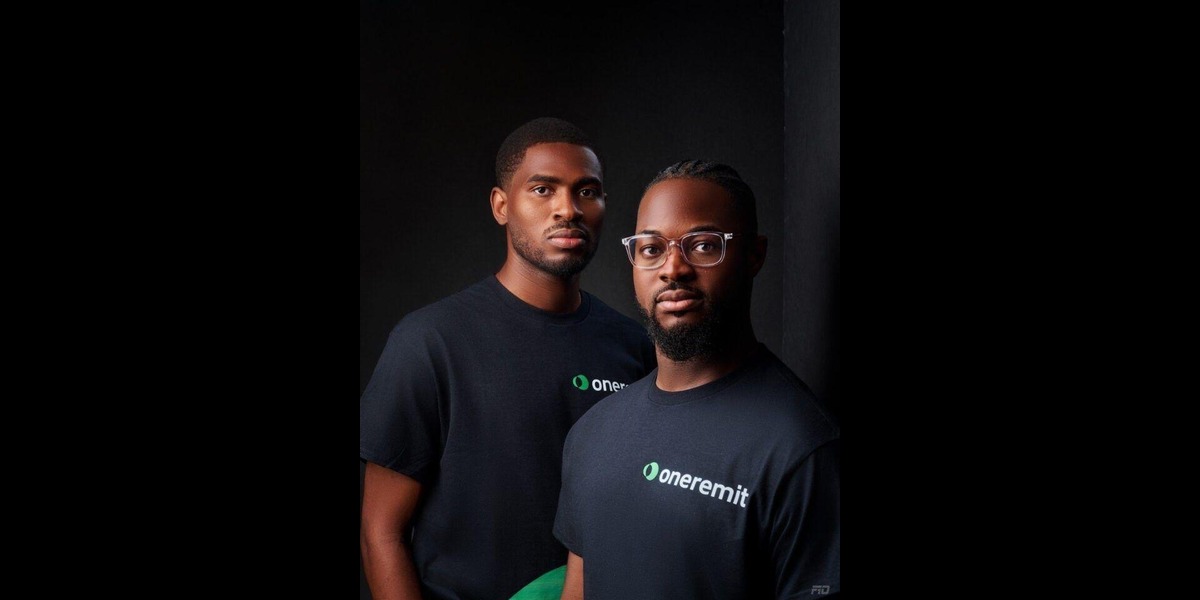
For Oneremit, operating across these multi-jurisdictional environments forms the backbone of its technical and legal architecture. As Hammed Afenifere, CEO and co-founder of Oneremit, notes: “Cross-border payments are not just about moving money from one country to another. You are operating across different financial systems, currencies, and regulatory environments. Building the right regulatory foundation means we can keep expanding what we offer businesses without compromising on compliance.”
De-Risking Corporate FX and Treasury Liquidity
Compliance becomes particularly important in business-to-business payments, where transaction values can be higher, and payments are often tied to time-sensitive commercial obligations.
For corporate finance teams, regulated cross-border infrastructure offers value beyond meeting legal requirements. Clearer compliance processes can reduce uncertainty around how transactions are screened, documented and processed, while access to supported local payment networks can improve settlement efficiency across different markets.
Oneremit combines its regulatory framework with access to payment routes including US ACH and Fedwire, European SEPA and SEPA Instant, and Canadian Interac and EFT. This lets the company route payments through infrastructure suited to the destination market while giving businesses greater visibility into FX pricing, transaction status, and settlement documentation.
For treasury teams managing repeated international obligations, that combination can improve predictability around payment costs and settlement timelines, while creating clearer records for reconciliation, audit and reporting purposes.
Regulatory Expansion as Growth Infrastructure
In under 2 years of operation, Oneremit has processed more than $200 million in cross-border business payment volume, as demand for international settlement among its enterprise customers has grown.
The company sees its four current regulatory milestones as a foundation for further expansion rather than an endpoint.
“Our goal is to make paying globally feel local for African businesses,” Afenifere added. “The complexity of moving money across currencies, banking systems, and jurisdictions should sit with the payment provider, not the business trying to pay its supplier.”
For African payment companies expanding beyond their home markets, regulation is increasingly becoming part of the infrastructure required for growth.
Technology can make a transaction faster or easier to initiate, but operating across multiple markets also requires providers to navigate the rules governing how those transactions are processed.
For Oneremit, its growing regulatory footprint is intended to support that next stage: expanding the markets and payment routes available to African enterprises competing in global markets while building within the compliance requirements of each jurisdiction.