 Follow Us on Google Discover
As Nigeria approaches the end of 2026, questions are mounting over the gap between improving macroeconomic indicators and actual budget delivery.
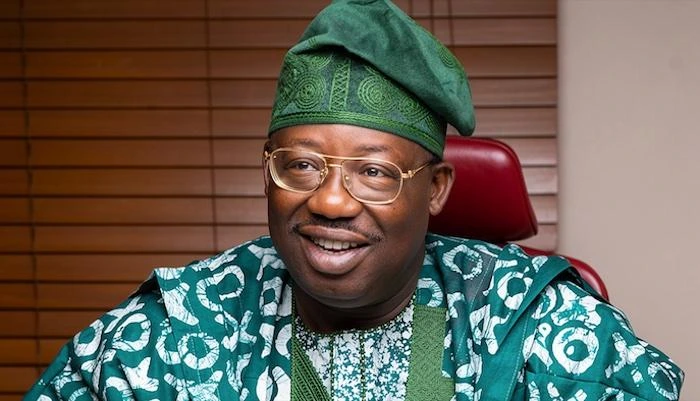
In this interview with Nairametrics, Hon. Dele Kelvin Oye, Esq., Chairman of Alliance for Economic Research & Ethics Ltd/GTE, examines the Federal Government’s budget performance, revenue generation, deficit financing, capital expenditure and mounting debt obligations.
He argues that while economic indicators such as GDP growth and inflation show signs of improvement, these gains must translate into completed infrastructure, reliable public services, job creation and lower business costs to improve living standards.
Oye also examines the implications of overlapping budget cycles, delayed capital implementation and growing borrowing requirements, outlining reforms he believes should shape the 2027 budget.
Also Read
Nairametrics: As 2026 advances towards year-end, how should Nigerians assess the Federal Government’s budget performance?
Oye: The fairest answer is mixed. We have seen improvement in important macroeconomic indicators, but those improvements must be judged alongside delivery.
The 2026 Appropriation Act was assented to on 17th April. The State House said it came into force on 1 April. That distinction matters: the late assent compressed the implementation timetable, but it would be inaccurate to say that the legal instrument did not exist until 17th April.
The National Bureau of Statistics reported real GDP growth of 3.89 per cent year-on-year in the first quarter and 4.43 per cent in the second quarter. Headline year-on-year inflation fell from 15.91 per cent in June to 14.63 per cent in September under the rebased CPI series. These are welcome signs of improving stability. They are not, by themselves, proof that households or businesses are better off.
The World Bank’s October assessment reported that distributed Federation Account revenues reached N10.479 trillion in the first half of 2026, equal to 4.2 per cent of GDP. In its federal fiscal comparison, it recorded reported capital spending of about N0.7 trillion, or 0.3 per cent of GDP, down from 1.0 per cent of GDP in the first half of 2025. That is not the same measure as the Budget Office’s broader N4.18 trillion total for first-half capital expenditure, which includes several separately classified and financed categories.
My assessment is therefore cautious: macroeconomic stabilisation is necessary, but it must lead to more reliable infrastructure, better public services, jobs and lower costs of doing business. A manufacturer still paying more to move inputs because a road is unfinished, or a farmer losing produce on the way to market, may not yet feel the improvement shown in a national indicator.
Nairametrics: How has the government performed on revenue, expenditure and deficit financing?
Oye: We must keep the proposal, the approved budget and actual performance separate. They are not interchangeable.
In December 2025, the President presented a N58.18 trillion proposal, with projected revenue of N34.33 trillion and a deficit of N23.85 trillion. The Budget Office’s approved-budget figures show aggregate expenditure of N68.32331 trillion, projected revenue of N36.86668 trillion and a deficit of N31.45663 trillion. The increase from the President’s proposal was about N10.14 trillion.
The approved deficit is about N85 for every N100 of projected revenue. The often-quoted N70-per-N100 comparison belongs to the original proposal, not the approved budget. The approved financing schedule lists N18.42819 trillion in domestic borrowing and N10.79037 trillion in foreign borrowing a combined N29.21856 trillion. It also lists N2.04892 trillion in project-tied multilateral or bilateral loans and N189.16 billion in privatisation proceeds. These are financing provisions, not proof that all funds have been raised or spent.
Higher revenue is valuable only when the public can see what it funds. For a family, the meaningful test is whether the clinic has essential supplies and the school can keep its doors open. For a business, it is whether power, transport and predictable public services reduce operating costs. Revenue reporting should therefore show, by period, what was forecast, collected, borrowed and spent and how those figures reconcile to the approved budget.
If a budget grows substantially after presentation, the government should publish a clear reconciliation of the additional amount by project, legacy obligation, ministry and financing source. This is a practical requirement for trust, not a communications exercise.
Nairametrics: What is your assessment of capital-budget implementation so far?
Oye: The most important point is to distinguish allocation from release, expenditure and completion.
The enacted budget provides about N32.29 trillion for capital expenditure. That is an appropriation. It does not mean that the same amount has been released, spent or converted into completed assets.
The Budget Office’s second-quarter implementation report records cumulative first-half capital expenditure of N4.17734 trillion across its broader capital categories. That total includes, among other items, 2025 capital carried into 2026, GOE capital expenditure, the Development Levy, TETFUND, project-tied loans and grant- or donor-funded projects. In the same report, implementation of the 2026 MDA capital budget remained at zero as at 30th June because agencies were still using funds from the extended 2025 capital programme.
The World Bank’s approximately N0.7 trillion measure is a narrower federal fiscal comparison. The Budget Office’s N4.18 trillion is a wider budget-execution total that groups several funding channels and carry-over items. They are different measures with different coverage; neither number should be substituted for the other.
This is not a call to stop every new project. It is a call to sequence projects honestly. When a road remains unfinished, truck costs can rise, produce can spoil before it reaches market, and local businesses lose time and money. Public investment should be planned around what can be funded and completed, not merely what can be announced.
A project should enter a new budget only when its design, land, procurement plan and funding path are credible. Completion should be measured by an independently verified, usable asset—not by a warrant, a contract award or a payment certificate alone.
Nairametrics: What are the implications of multiple budget sessions and overlapping fiscal commitments?
Oye: The President’s December 2025 commitment was clear: Nigeria would end the practice of running multiple budget cycles at once and move towards a single budget and revenue cycle.
The implementation history has not matched that timetable. The capital component of the 2025 appropriation was carried beyond its original year and extended through a series of legislative changes, most recently to 31st December 2026. The extensions were made through law, but they mean that 2025 capital commitments continue alongside the 2026 budget.
That overlap makes it harder to answer a basic question: which budget year paid for a project, and what was delivered from that year’s appropriation? It can also complicate cost control and public oversight. These are serious risks even where an extension is legally authorised.
At each year-end, government should publish a short close-out statement identifying the value of carry-over commitments, the reason each remains outstanding and the date by which it will be resolved. That fiscal close-out should complement, not replace the project-level delivery.
Nairametrics: Have repeated adjustments and rollovers weakened the 2026 budget’s execution?
Oye: They have made the budget harder to read and harder to hold to account. But an adjustment is not automatically a failure. In some cases, completing a viable project is better than abandoning it because the calendar has changed.
The key question is whether each addition is funded, ready and transparently reconciled. The approved budget is about N10.14 trillion larger than the President’s December proposal. That increase should be explained line by line, not merely announced as a larger envelope.
There is a material discrepancy in the oil-price assumption. The President’s proposal and BudgIT’s analysis of the approved budget identify US$64.85 per barrel. It was reported that the Appropriations Committee chairman said the benchmark was raised from US$65 to US$75. Government should publish the authoritative fiscal assumptions and clarify which figure governs.
A credible budget should be honest about uncertainty. It can set a base case, a downside case and a trigger for corrective action. What undermines trust is presenting an uncertain assumption as guaranteed cash, then asking the public to accept repeated revisions without a transparent explanation.
Nairametrics: Where is the disconnect between allocations, releases and completed projects?
Oye: The disconnect lies in the hand-offs. An appropriation authorises spending. It does not, on its own, provide cash, complete procurement, ensure timely payment or verify that an asset works.
The Budget Office’s latest implementation report identifies practical execution concerns, including cash planning, release predictability, commitment control and project monitoring. It also reports that implementation of the 2026 MDA capital budget had not commenced by 30 June while prior-year capital funds were still being used. These are specific institutional problems. They are more useful to address than saying, without evidence, that every stage of the system is failing.
My proposal is one public project record from approval to operation. It should show the budget year and location; the contract and contractor; amounts appropriated, released and paid; independent physical-progress checks; and a completion certificate confirming that the asset is usable. Agencies, the National Assembly and civil society should work from the same record.
We should also stop repeating abandoned-project totals as if they were current, verified national inventories unless the source, date, scope and method are disclosed. Nigeria needs a reliable register more than another alarming headline figure.
I would not impose a blanket two-year freeze on all new projects. Some new investments are urgent and ready. Instead, review ongoing projects by public value, cost to complete and realistic delivery time, while requiring every proposed new project to pass a readiness test. That favours completion without freezing development.
Nairametrics: Is government allocating enough to capital investment given debt and recurrent pressures?
Oye: On paper, the allocation is substantial: about N32.29 trillion, or roughly 47 per cent of the approved N68.32 trillion budget. But the capital allocation is not the same as capital delivered.
The approved-budget schedule groups debt service and the sinking fund at approximately N15.81 trillion. Separately, the World Bank puts consolidated debt service at 49.5 per cent of revenue in 2025.
These are not like-for-like figures: one is a 2026 Federal Government budget provision; the other is a 2025 outturn across the Federal Government, states, Federal Capital Territory and local governments. The latter is neither the Federal Government’s debt-service allocation nor its interest bill.
The Debt Management Office reported total public debt of N166.79 trillion, about US$120.93 billion, at 30th June 2026, compared with N87.38 trillion at 30th June 2023. This is a broad public-debt stock, and changes reflect more than new borrowing alone, including valuation effects and the recognition of older liabilities.
The budget’s N29.22 trillion domestic and foreign borrowing provisions are plans, not completed transactions. Likewise, the US$7.7 billion external borrowing plan requested from lawmakers in November should not be described as approved or drawn down unless that happens and is documented.
High government financing needs can make credit more expensive and compete with private borrowers for funds. For a manufacturer, that can mean postponing a new machine or a new hire because financing is too costly. That is a serious crowding-out risk, but it should be measured rather than asserted as a universal outcome. The practical response is to reduce avoidable borrowing, improve the quality of public investment and deepen long-term local-currency finance.
Nairametrics: How transparent and accountable do you think has implementation of the 2026 budget been?
Oye: The record is mixed. Important information is published. For example, FAAC reported that N2.428823 trillion was distributed from September 2026 Federation revenue, out of gross revenue of N3.913 trillion. Those are different figures and should not be described as if the distributable amount were gross revenue collected.
The project record should be the common source of information for government, lawmakers, journalists and civil society. The remaining accountability task is to publish what oversight finds and what agencies do in response.
The Constitution and the Fiscal Responsibility Act provide important powers and duties for appropriation, legislative oversight, transparency and budget reporting. Nigeria’s Open Government Partnership action plan also includes commitments on openness and public participation, but an OGP commitment is not itself a statutory right to every project-level record.
The National Assembly should publish findings from oversight visits and show whether agencies acted on them. Audit reports must also receive a formal response: the responsible agency should state whether it accepts each finding, what corrective action it has taken and when outstanding issues will be resolved. Publishing a report is the start of accountability, not its conclusion.
Nairametrics: What obstacles could still derail the 2026 targets, and what should be done immediately?
Oye: There are four risks to watch closely.
First, election-period spending can put pressure on the deficit and financing needs. The World Bank identifies higher pre-election spending as one factor that could widen the consolidated deficit in 2026. That is a risk to manage, not a claim that every public project will be diverted for political purposes.
Second, revenue depends on assumptions that must be tested. The public record should resolve the oil-benchmark discrepancy and report oil price, production, collections and remittances against the same published baseline. A sensitivity estimate should show the assumptions behind it rather than offer a single naira loss figure without a transparent fiscal model.
Third, the 2025 capital extension runs to 31st December 2026. That creates a risk that agencies will be managing old obligations while trying to start new work. The year-end close-out statement I earlier proposed can make the scale of this overlap visible.
Fourth, security shocks can affect oil production, agriculture and project execution. The IMF identifies domestic security as a downside risk to economic performance. The response should be targeted to affected areas and sectors, with clear evidence of the disruption and its fiscal cost.
For the remaining weeks of 2026, government should close the 2025 capital programme on the statutory date and explain any unresolved liability. It should avoid fresh discretionary commitments that cannot be funded and delivered within a credible timetable, while protecting essential and ready projects. Before the 2027 budget begins, it should publish a realistic first-quarter cash plan based on confirmed resources.
Nairametrics: What fundamental reforms should shape the 2027 budget?
Oye: The first reform is to enforce the financial year Nigeria already has. The Financial Year Act sets a January-to-December cycle. Government and the National Assembly should agree and publish a binding timetable for budget presentation, scrutiny, passage and implementation. Any default-spending arrangement for a late budget should be designed in law; it should not be presented as if a one-twelfth recurrent rule or a ban on all capital commitments already exists.
The second is to make revenue assumptions independently testable. Publish the data, methodology and downside case behind oil, tax and other receipts. Section 18 of the Fiscal Responsibility Act already makes the Medium-Term Expenditure Framework the basis for annual revenue and expenditure estimates. The task is to make that framework credible and enforceable.
The third is project readiness. Before a project enters the budget, establish that its design, land status, procurement plan, cost to complete and provision for maintenance are credible. This prevents an appropriation from being mistaken for a shovel-ready project.
The fourth is disciplined sequencing. Review existing commitments and complete viable projects before adding lower-priority work. New projects should be selected on public value and readiness, not on the visibility of a groundbreaking ceremony.
The fifth is disciplined borrowing. Enforce the Fiscal Responsibility Act’s existing borrowing-purpose rules and publish borrowing authorised, borrowing raised, debt service and the use of proceeds in one quarterly statement.
I would support a pathway to reduce the consolidated debt-service-to-revenue ratio to 40 per cent by 2028. The World Bank puts the comparable 2025 baseline at about 49.5 per cent, so 40 per cent would mean a reduction of 9.5 percentage points over three years.
I choose it as an intermediate fiscal guardrail not because 40 per cent is a universal statutory threshold or a magic number. The target should use the same published definition each year, include annual milestones and be revised transparently if the underlying revenue base changes. At 40 per cent, a larger share of comparable revenue would remain for other public purposes, though it would not all be freely available for capital spending.
My years in business leadership and board service have taught me that a plan is credible only when responsibility, funding and delivery are visible. The 2027 budget should be prepared earlier, costed honestly and sized to the resources the country can realistically mobilise. It should also finish more of what Nigerians have already paid for.
At the Alliance for Economic Research and Ethics, our standard is straightforward: growth is a means; development that is human, shared and visible is the destination. The 2026 budget’s lesson is not that Nigeria should stop aspiring. It is that ambition must be matched by the institutions, cash plans and public reporting needed to deliver it.
A budget is not the value printed on its cover. It is the school opened, the road completed, the clinic equipped, the farm connected to a market and the business able to borrow and grow. That is the test Nigerians are entitled to apply.
As the proverb reminds us, a tree is known by its fruit. A budget, too, should be judged by what it delivers to the people.