 Follow Us on Google Discover
Financial services executives are pushing for wider adoption of tokenised payments in Nigeria, citing the technology’s potential to reduce fraud risk and strengthen transaction security.
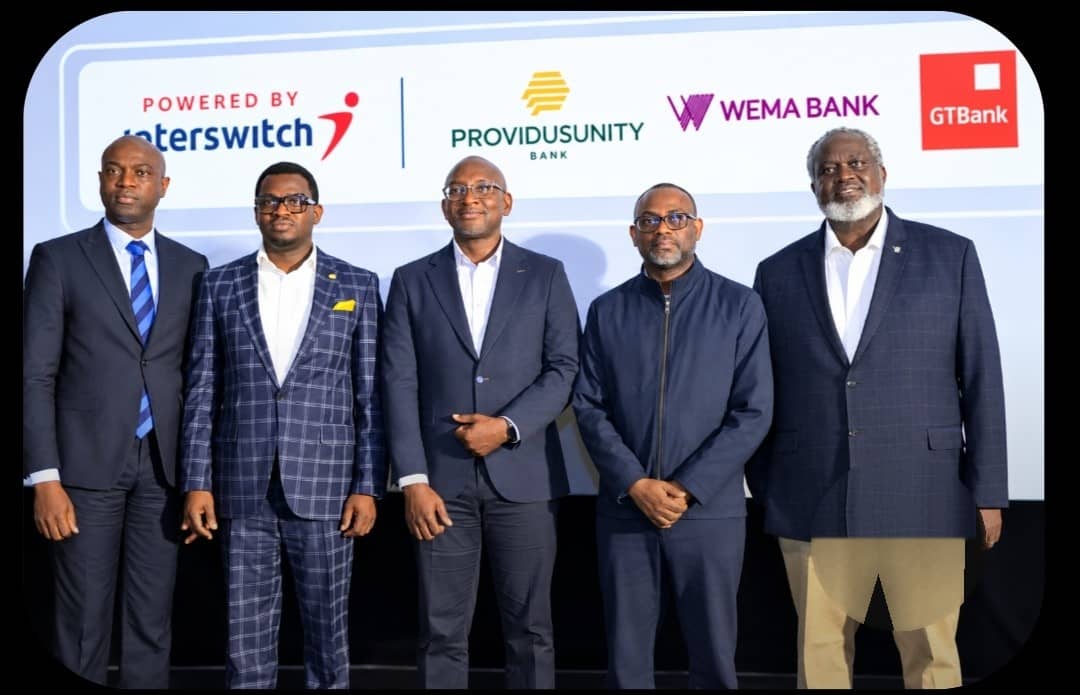
The executives from Verve International, GTBank, Wema Bank and ProvidusUnity Bank spoke at the Interswitch Tokenisation Documentary Press Briefing, where they highlighted how tokenisation could protect customers’ card details while making digital payments faster and more convenient.
Payment tokenisation replaces sensitive card information, such as a card’s primary account number, with a substitute identifier known as a token. The token can facilitate eligible transactions without exposing the underlying card details.
The executives said the technology could limit fraudsters’ ability to exploit stolen or exposed card information, particularly as more Nigerians embrace digital transactions and smartphone-based payments.
Also Read
Tokenisation to strengthen payment security
The Managing Director for Payments, Switching and Processing at Interswitch, Akeem Lawal, described tokenisation as a major shift in payment security, arguing that it reduces the risk of card details being compromised.
- “We believe that tokenization is one of such industry-changing innovations. We believe that it is a step change in the security of payments transactions, because it takes away the ability of fraudsters to compromise your payment card by replacing that card information with a token that is useless to anyone else,” Lawal said.
He explained that conventional card payments can expose customers to risks when their card numbers and expiry dates are seen by others, when someone observes them entering their PIN or when card details are exposed during online transactions.
- “With tokenisation, the only thing that they see is a token.”
According to Lawal, the token is linked to the actual card number but is not the same as the underlying card information. He said the token would be of no use to someone who obtained it, while encryption links it to the user’s phone.
Lawal said the technology builds on earlier payment security developments, including chip-and-PIN cards, while supporting a shift towards contactless transactions.
He recalled that Interswitch pioneered interbank ATM switching in 2002 before expanding into point-of-sale and online payments and developing a domestic card scheme. He said each innovation, introduced in collaboration with industry partners, had changed how payments were conducted in Nigeria.
According to him, the next phase of consumer payments would move towards “just tap,” following the progression from swiping and inserting cards to transfers and contactless payments.
Phone-first consumers drive adoption
The Executive Director, Retail and Digital Business at Wema Bank, Tunde Mabawonku, said tokenisation was increasingly relevant as consumers moved towards digital transactions.
He observed that Nigerians readily share their account numbers, but said protecting payment instruments was becoming more important as transactions shift online.
- “As we move to digital transactions, the next best thing is to tokenize your payment instruments,” he said.
Mabawonku said younger consumers were more likely to leave their debit cards at home than their phones, creating opportunities for mobile-based payments.
He expects consumers to increasingly use their phones to pay for transport and other services in Nigeria and abroad.
- “Tokenization is here to stay,” he said.
Contactless demand gains momentum
The Divisional Head, Digital Banking and Financial Inclusion at GTBank, Jimmy Banjoko, said demand for contactless payment options increased after the COVID-19 pandemic.
He said the trend pointed to growing consumer interest in payment methods that reduce physical contact, adding that GTBank worked with Interswitch on the solution and was among the pioneering banks to launch it.
Banjoko expects tokenisation to move customers from payments initiated within banking applications towards simpler tap-based transactions.
He said the technology could become “the mainstream of payments” in the near future.
Fewer payment steps, added security
The Chief Executive Officer and Managing Director of Verve International, Vincent Ogbunude, said tokenisation could simplify the payment process while strengthening security.
He noted that a bank transfer could involve five or six steps, while conventional card payments require customers to retrieve their cards and enter a four-digit PIN.
By contrast, he said tokenised payments could require “no more than two steps,” with users verifying their identities through methods such as fingerprint authentication.
Ogbunude said incorporating the customer’s identity into the payment process could provide an additional layer of security while reducing the need to carry physical cards.
He added that Verve was working with phone manufacturers, including Apple and Google, to advance its contactless payment offering.
He described the initiative as positioning Verve as “an African-first scheme of global importance.”
ProvidusUnity targets wider adoption
The Divisional Head, Digital Banking at ProvidusUnity Bank, Elliott Sangoleye, said Providus Bank pioneered tokenisation in sub-Saharan Africa before its merger with Unity Bank in 2026.
He said the bank had enabled customers to make payments at point-of-sale terminals using phones, rings and watches.
Following the merger, Sangoleye said the enlarged institution, which has more than 223 branches, would need to extend the platform to more customers and merchants to encourage wider adoption.
- “We welcome anyone that will join us on this journey to push the frontier of tokenization,” he said.
Tokenisation extends beyond payments
The push for tokenised payments comes amid broader interest in tokenisation across financial services, including the digital representation of assets for investment and trading.
Roqqu Chief Executive Officer Eseoghene Onomor recently said tokenisation would drive the next $10 trillion in on-chain assets, as the digital asset company works on infrastructure that could connect Nigerian stocks with investors in global markets.
Onomor said the Dangote Refinery initial public offering (IPO) had renewed attention on investment opportunities in Nigeria, adding that Roqqu aims to expand access to locally issued assets through digital channels for international investors.
While payment tokenisation replaces sensitive card details with substitute identifiers to facilitate transactions, asset tokenisation involves digitally representing ownership or rights to assets. Both use token-based systems but serve different purposes.