 Follow Us on Google Discover
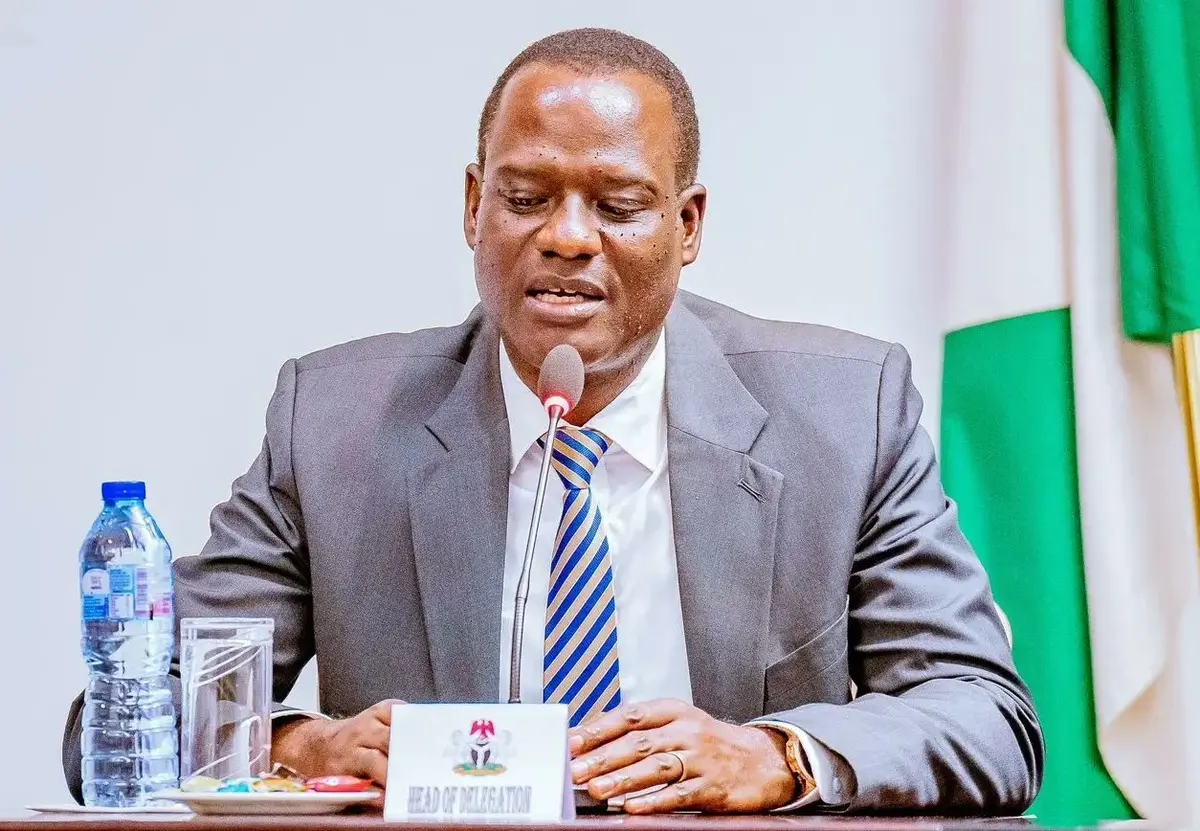
The Federal Government has unveiled a draft Economic Policy Framework for Nigeria aimed at promoting policy consistency, strengthening investor confidence and driving sustainable economic growth.
Finance Minister and Coordinating Minister of the Economy Taiwo Oyedele announced the framework at the 32nd Nigerian Economic Summit (NES32) in Abuja on Monday, October 26, 2026. The summit was themed “Growth that Works: Delivering Jobs, Productivity and Shared Prosperity.”
The proposed framework is designed to guide government plans, budgets and policies regardless of the administration in power, providing a long-term basis for economic decision-making.
Oyedele Targets Policy Consistency and Investment
Oyedele said Nigeria’s main economic challenge was not a shortage of development plans but the absence of an enduring economic philosophy and disciplined implementation.
Also Read
He said frequent policy reversals, inadequate consultations and decisions unsupported by credible data had weakened businesses, discouraged investment and limited job creation.
The minister described policy uncertainty as an additional burden on businesses, arguing that it discourages investment without generating revenue for the government.
“Policy uncertainty is an invisible tax on enterprise and unlike most taxes it generates no revenue for government. It only destroys value and discourages investment,” he said.
Oyedele said the proposed framework was neither a development plan, a catalogue of capital projects nor a political manifesto, but a national economic doctrine to guide economic decisions.
“Our vision is simple but profound: a productive, competitive, diversified and inclusive economy that delivers quality jobs, expands real household incomes and creates shared prosperity,” he said.
He added that economic progress should be measured by improvements in citizens’ livelihoods, including productive employment, higher agricultural yields and the growth of small businesses.
While gross domestic product (GDP) growth remained important, Oyedele said improvements in per capita income and domestic capital formation were also essential to translating economic expansion into better living standards.
FG Outlines Seven Pillars of Economic Policy
The minister identified seven interconnected systems underpinning the proposed framework: stability, productivity, enterprise, capital, people, markets and institutions.
He said these systems must function together to build a resilient economy, supported by efficient infrastructure, logistics, education, healthcare and human capital development.
Oyedele also outlined three non-negotiable principles for economic management.
Enterprise should serve as the engine of economic growth, with private businesses driving production and employment.
Markets should remain open but fair, allowing competition while supporting the development of competitive local industries.
Government policymaking should be coordinated, with institutions considering the cumulative effects of their decisions on businesses and the wider economy.
He said government should provide public goods, uphold the rule of law, address market failures and protect vulnerable citizens.
On industrial policy, Oyedele argued that tariffs should help local industries become competitive rather than provide permanent protection from competition.
He stressed that the framework remained a consultation draft and had not yet become approved government policy.
Public consultations are scheduled to run until November 27, with Nigerians invited to respond to 17 core questions through the Ministry of Finance website.
According to the minister, the framework will proceed to the Federal Executive Council for approval and the National Economic Council for endorsement after validation.
He urged the Nigerian Economic Summit Group and private sector stakeholders to scrutinise the draft, provide evidence-based recommendations and help build national consensus.
What you should know
In June 2026, Nairametrics reported that Oyedele had said the Federal Government would adopt a new framework for assessing Nigeria’s economic performance.
The minister said the government was shifting its focus from headline growth figures to measurable improvements in living standards and shared prosperity.
He outlined plans to assess economic performance using indicators that more directly reflect the welfare of Nigerians.
These include reductions in multidimensional poverty, growth in real income per capita and declining levels of inequality.
Oyedele also said the government would provide regular updates on the indicators to improve accountability to citizens.
The approach is intended to assess economic performance based on outcomes that directly affect households rather than relying solely on traditional growth statistics.
The proposed economic policy framework builds on this emphasis by seeking to establish consistent principles for policymaking and measurable indicators that can guide successive administrations.