 Follow Us on Google Discover
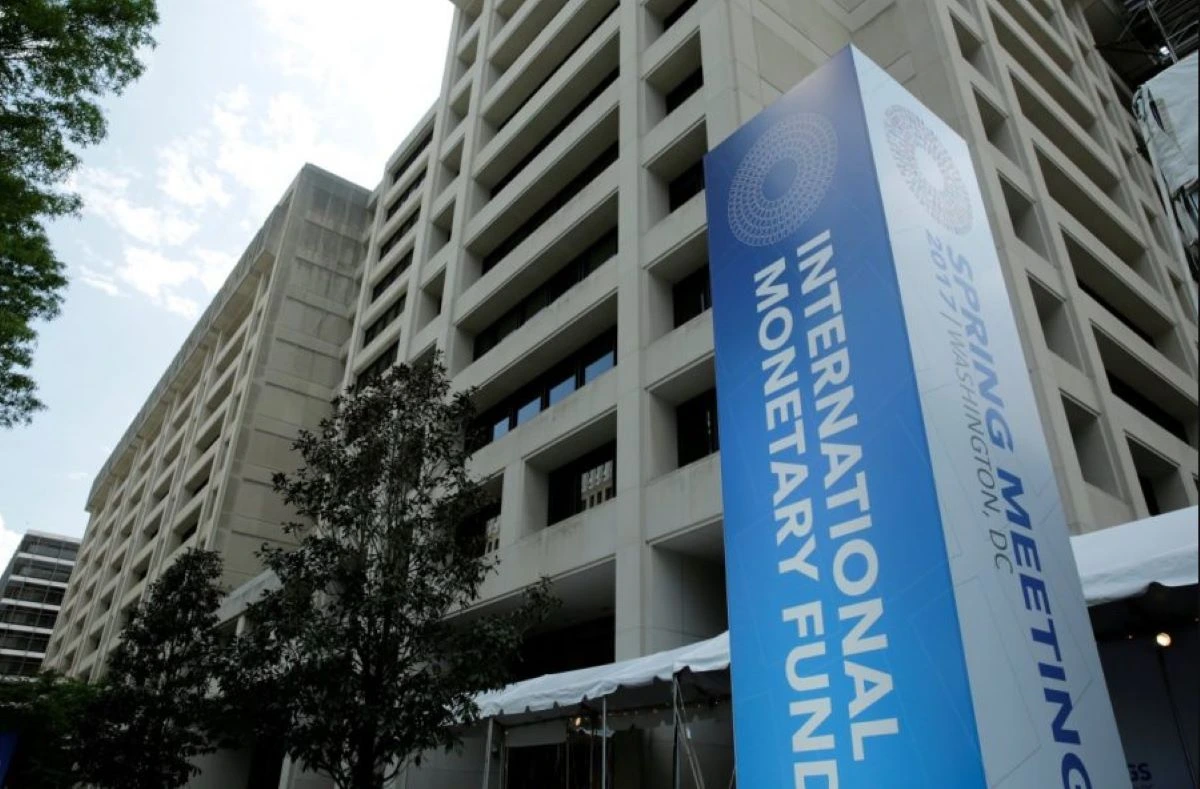
The International Monetary Fund (IMF) has identified over-optimistic tax revenue projections, weak policy implementation and limited administrative capacity as key reasons governments often fall short of their revenue targets.
A study titled Understanding Over-Optimism in Tax Revenue-to-GDP Forecasts under IMF-supported Programs, authored by Jean-Marc Atsebi, Qiaoe Chen, Nikolay Gueorguiev and Magali Pinat, examined tax revenue forecasts under IMF-supported programmes between 2015 and 2024.
The study found that these programmes projected a median increase of 1 percentage point in the tax revenue-to-GDP ratio by the third year, but the actual median increase was only 0.3 percentage point, highlighting a substantial gap between expected and realised revenue gains.
Why tax revenue targets are being missed
The IMF study identifies several factors behind the gap between projected and actual tax revenue, including overestimated yields from tax policy measures, unrealistic assumptions about tax buoyancy, macroeconomic forecast errors and expectations that governments will fully implement planned reforms.
Also Read
- “A key finding is that over-optimism in tax policy yield estimation, policy implementation expectations, and tax buoyancy assumptions plays a central role in explaining these forecast errors, alongside macroeconomic forecast errors and a residual optimism,” the organisation noted.
Tax policy yield estimates are particularly important because they determine how much additional revenue governments expect to collect from new taxes or changes to existing tax rules. However, the study finds that more than half of projected tax policy yields often fail to materialise.
- Tax buoyancy assumptions also influence revenue forecasts by estimating how tax collections will respond to economic growth. When economic performance or the relationship between growth and tax receipts differs from expectations, actual collections may fall below projections.
The researchers also identify residual optimism in revenue forecasting, suggesting that forecast errors cannot be fully explained by the measured economic and policy factors alone.
- “When revenue measures are well-designed, fully implemented, and accompanied by high-depth revenue-related structural reforms, projected revenue gains materialize to a large extent. This implies that over-optimism emerges primarily when ambitious revenue targets are not supported by sufficiently deep and well-implemented reforms,” IMF noted.
Tax administration and implementation remain critical
The study highlights tax administration capacity as an important factor in reducing forecast errors. Governments with stronger administrative institutions are better positioned to implement tax measures and translate policy changes into actual collections.
- The findings suggest that introducing new taxes or increasing existing rates may not be sufficient to deliver projected revenue gains. The design of tax measures, the government’s ability to implement them fully and the depth of revenue-related structural reforms also matter.
The IMF researchers recommend further investigation into how political conditions, including elections and instability, affect tax revenue outcomes. They also identify the need for more research into forecast errors across different tax types and bases, as well as the effects of tax evasion and compliance.
Nigeria’s tax reforms face implementation challenges
Nigeria introduced four major tax reform laws that took effect in January 2026: the Nigeria Tax Act, Nigeria Tax Administration Act, Nigeria Revenue Service (Establishment) Act and Joint Revenue Board (Establishment) Act.
The reforms seek to harmonise tax administration, eliminate duplicate taxes, improve compliance, broaden the tax base and reduce the burden on small businesses.
- However, businesses have continued to report concerns about multiple taxes, levies and other government collections, raising questions about how effectively the reforms are being implemented across different levels of government.
- The IMF’s findings are relevant to Nigeria’s reform agenda because they highlight the difference between the revenue gains governments anticipate from policy changes and what they ultimately collect. Stronger administrative capacity, effective implementation and improved compliance are important to closing that gap.
In a separate analysis, the IMF has also highlighted the potential revenue benefits of stronger anti-tax-avoidance reforms for emerging market and developing economies. Such measures could help limit profit shifting and protect domestic tax revenues.