 Follow Us on Google Discover
Lagos-based Regxta Global Services Limited has disbursed more than ₦10 billion in loans to individuals and micro-business owners across Nigeria, as the lender expands a credit model designed for borrowers who may have little or no conventional credit history.
The milestone comes against a broader challenge facing many small businesses and informal-sector borrowers, where access to credit often depends on formal identification, documented income, collateral and an established borrowing history, information many micro-business owners do not always have.
To address that gap, Regxta developed a lending model that combined alternative customer data with an agent-led distribution network.
Since the platform went live in October 2023, the company says it has written more than 100,000 loans and onboarded 35,000 customers.
Before the platform was introduced, much of Regxta’s loan record-keeping and monitoring was handled manually. That made it more difficult to maintain an immediate view of the loan book or identify repayment problems as they developed.
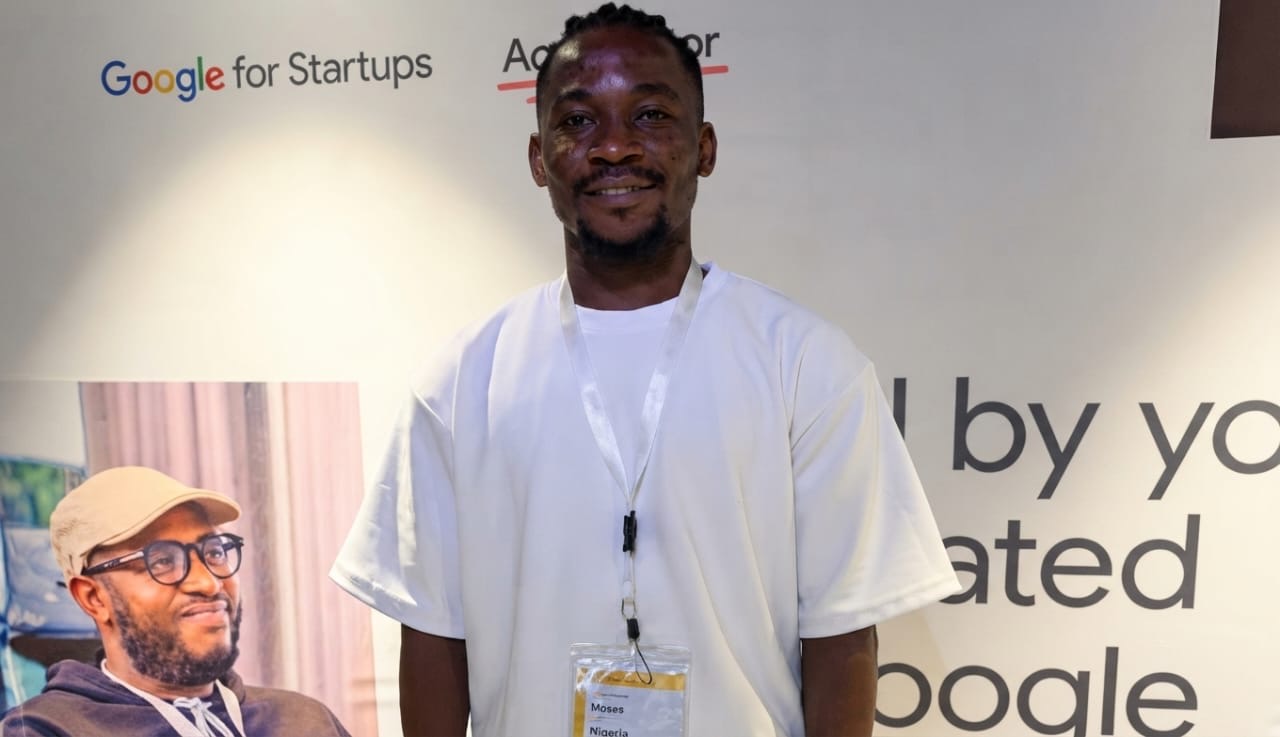
“The goal was to move the company away from managing loans through scattered manual processes,” Chief Technology Officer Moses Obika said. “We needed to know what was happening across the portfolio as it happened, not piece that information together weeks later.”
The platform introduced a central system for tracking loan activity while allowing field agents to receive alerts when customers begin falling behind on repayments. It also brought parts of customer verification, loan applications, approvals and disbursements into the same digital process.
Development of the system was led by Obika, who joined Regxta as a contract engineer in August 2021 before becoming CTO in September 2022.
“We spent about a year building before we put anything live,” Obika said. “The system had to assess customers who have no credit history and no collateral, and it had to give us visibility into the portfolio in real time rather than weeks after the fact.”
That lack of conventional borrower information shaped how the lending system was built.
Rather than depending entirely on traditional credit records, Regxta uses alternative information generated through its lending process alongside its agent network to assess and monitor customers.
For borrowers, Obika said the value of that system is the opportunity to establish a financial record even when they enter without one.
“Someone may come to us without a credit file or collateral, but that should not mean there is nothing to assess,” Obika said. “Once they begin borrowing and repaying, they are building a record of their own. That gives us more information to work with the next time they need credit.”
The agent network also remains part of how the company reaches customers who may not complete an entirely digital lending process on their own.
Regxta’s lending volumes have grown alongside the platform. The company recorded ₦10,000 in lending during the system’s first month of operation. In 2026, monthly lending volumes rose to more than ₦650 million, according to company figures, with more than 4,000 loans now processed each month.
The increase has also given Regxta a larger pool of repayment information from customers whose borrowing activity may otherwise sit outside conventional credit reporting systems.
That data can provide a record of how customers borrow and repay over time, giving the lender more information to use when making subsequent credit decisions.
Beyond lending, Regxta also provides savings, payments and digital banking services through its technology platform and agent network.
Its lending operation, however, remains focused on individuals and micro-business owners whose financial activity may not fit neatly within the requirements of traditional institutions.
The growth from ₦10,000 in lending during the platform’s first month to more than ₦10 billion in cumulative disbursements also reflects the technology challenge Obika was brought in to address: moving an existing lending operation from largely manual processes to a system capable of recording customers, monitoring repayments and managing a growing loan book in real time.