 Follow Us on Google Discover
Share prices of Nigeria’s largest listed companies have run well ahead of their latest earnings growth this year. That raises an important question for investors: how much of the market’s optimism is already priced in?
The backdrop is an exceptional year for Nigerian equities.
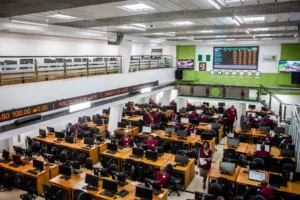
The NGX All-Share Index had gained about 61% year-to-date by September 21, crossing the 250,000-point mark. On September 23, it closed at a record 251,191.02 points, and total market capitalization reached an all-time high of N163.06 trillion.
That makes the performance of the SWOOTs, or Stocks Worth Over One Trillion naira, particularly important. The 25 companies in this group now have a combined market value of about N148.86 trillion. That is 91.3% of the NGX’s total market capitalization, which shows how heavily the market is concentrated in its largest stocks.
Also Read
The SWOOTs’ combined market capitalization has risen by about N59.18 trillion in 2026, from about N89.68 trillion at the start of the year. That is a 66% increase. In September alone, they added about N4.54 trillion, or about 3.1%, from an estimated N144.32 trillion at the end of August.
With that level of concentration, SWOOT share prices largely decide where the market goes. It also makes the link between their valuations and their earnings critical. If the biggest stocks are rising faster than their profits, a growing share of the rally is coming from investors paying more for each naira of earnings, not from companies earning more.
Nairametrics’ review of these companies shows exactly that disconnect. For most of them, 2026 share-price gains have outpaced growth in their latest comparable earnings per share. Only four have earnings growth running ahead of their year-to-date share-price performance: MTN Nigeria, BUA Foods, BUA Cement and Nigerian Breweries.
This does not mean the rally is unjustified. Share prices reflect expectations about future earnings, not just profits already reported. But when prices rise far faster than current earnings, the burden shifts to future results. Companies must now deliver the growth that investors are already paying for.
What the 25 SWOOTs are telling us
The earnings picture is much less aggressive than the share price rally. Nairametrics compared each company’s year-to-date share-price return with its latest comparable EPS growth.
For most companies, that means H1 2026 against H1 2025. For Zenith Bank, UBA, GTCO, Stanbic IBTC and Access Holdings, it means first-quarter results, where half-year numbers were not yet available.
The gap is clearest among the year’s biggest winners. Seplat’s share price is up 156.6% year-to-date, while its latest EPS growth is about 27.1%.
- Aradel has gained 128.4% against EPS growth of only 6.3%.
- HBM Nigeria has risen 167.4%, compared with 56.9% earnings growth, and FirstHoldCo’s 244.5% rally is well ahead of its 71.6% EPS growth.
- The gap is even wider in banking. Zenith Bank has gained 118.5% even though its latest EPS was almost flat, and Wema Bank has risen 55.9% despite a decline in earnings.
- GTCO, Access Holdings, ETI and Fidelity Bank have also rallied alongside weaker latest earnings.
Put simply, share prices have risen much faster than profits for some of these companies. That means investors are now paying more for every N1 of earnings than they were at the start of the year.
- Seplat and FirstHoldCo’s price-to-earnings ratios have roughly doubled, while Aradel’s has more than doubled. Zenith Bank’s valuation has also risen sharply even though earnings have barely moved.
- But the companies are not starting from the same place. At current prices, investors are paying about N21 for every N1 of Seplat’s earnings and roughly N16 for every N1 earned by Aradel.
The banks are still much cheaper. Zenith, GTCO and Wema trade at around five to six times earnings, while Access Holdings is closer to 2.5 times. So even though their share prices have risen strongly, they started with much lower valuations. That gives them more room than companies whose prices have already moved to much higher earnings multiples.
So, a stock rising strongly does not necessarily mean it has become too expensive. Investors may simply be expecting profits to improve later in the year, interest rates to fall or business conditions to get better.
What matters is that, for many of these SWOOT stocks, share prices have risen faster than actual earnings so far. In other words, part of this year’s rally is being driven by expectations of stronger future profits, not just the profits companies have already reported.
Four stocks still have earnings ahead of prices
Only four SWOOT stocks clearly have earnings growing faster than their share prices.
- BUA Foods stands out most: EPS rose 12.4%, while the stock is down 4.8% YTD.
- BUA Cement’s EPS grew almost 80%, ahead of its 66.4% share-price gain.
- MTN Nigeria’s earnings grew 70.5%, slightly faster than its 66.3% rally.
- Nigerian Breweries shows a smaller gap, with EPS up 5.3% against a 3.5% price increase.
Airtel Africa is not included because its reporting calendar is different. Although the stock is up 177.5% this year and earnings have recovered strongly, its latest results are not directly comparable with the half-year figures used for most of the other companies.
- Even among the four, the story is different. MTN and BUA Cement are currently growing earnings faster than their longer-term pace, suggesting stronger momentum.
- BUA Foods is the opposite: its latest 12.4% EPS growth is far below its five-year average of about 61%.
- Nigerian Breweries is still rebuilding earnings after the heavy losses recorded in 2023 and 2024.
So, earnings running ahead of share prices does not automatically mean a stock is cheap. The important question is whether that earnings growth can continue.
Which SWOOTs can grow into their prices?
MTN Nigeria and BUA Cement are in the strongest position. Both stocks are up more than 60% this year, but earnings have grown even faster. That means profits are already doing much of the work needed to support the rally.
- Dangote Cement and HBM Nigeria are close behind. Their share prices have risen faster than earnings, but not by an extreme amount. EPS growth of 24.3% for Dangote Cement and 56.9% for HBM Nigeria means profits are still moving in the right direction.
- The banks are different. Zenith, GTCO, Stanbic IBTC and Access Holdings still trade on relatively low earnings multiples, so their rallies do not automatically make them expensive.
- But Q1 2026) earnings are almost flat at Zenith and have fallen at GTCO and Access. Stanbic, with 14.4% EPS growth, is the stronger case. For the others, future results need to justify optimism already in their share prices.
The biggest challenge is with Seplat, Aradel and FirstHoldCo. Their share prices have moved far ahead of current earnings. Aradel looks particularly stretched because the latest EPS growth is only 6.3%.
The message is simple: the next stage of the SWOOT rally may depend more on profits catching up than on share prices rising further.
Investor takeaway
For investors, the lesson is simple: share-price gains are easier to justify when profits are rising alongside them. Where prices have moved much faster than earnings, future results now have more work to do.
That does not automatically make those stocks unattractive. But if profits fail to improve as expected, their share prices could come under pressure.
Stocks such as MTN Nigeria and BUA Cement are in a stronger position because earnings are keeping pace with their rallies. Others, including Seplat, Aradel and some banks, now need stronger earnings growth to justify how far their share prices have already moved.