 Follow Us on Google Discover
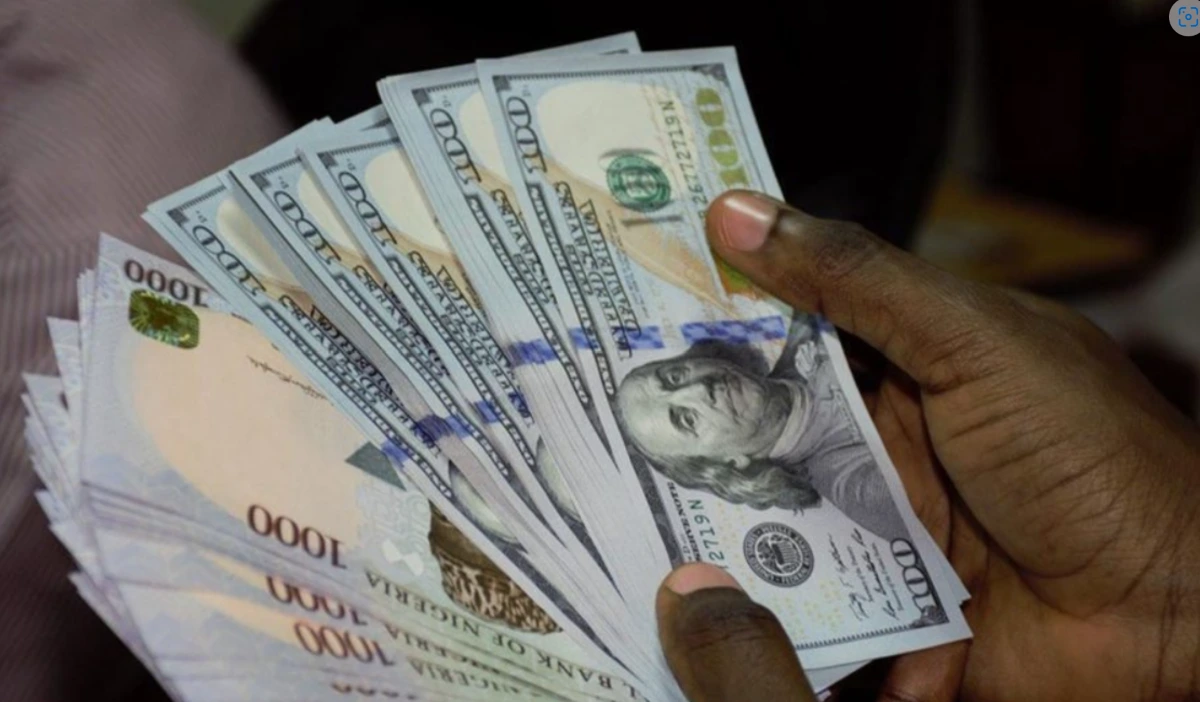
Emeka Nwosu sells phone accessories from a glass counter in Computer Village, Ikeja, and every morning before he opens he checks the rate on his phone the way a farmer checks the sky.
He has never bought a dollar in his life, but everything on his counter was imported and priced in dollars somewhere up the chain.
When a customer showed him the news that the Naira might go to N500 to the dollar if a particular candidate wins in 2027, Emeka did not ask whether it was possible.
He asked what would happen to the four million Naira of stock in his store room, bought at N1,350. Nobody at the press conference had thought about Emeka’s store room. Exchange rate promises are announced as gifts to consumers and arrive as a bill for somebody.
Also Read
The promise came on 30 October 2026 from Professor Pat Utomi, political economist and chieftain of the Nigeria Democratic Congress, who said its 2027 candidate, Peter Obi, was targeting a strategic appreciation of the naira from N1,350 to N500 per dollar, a 63% reduction in the exchange-rate quotation.
His accompanying price list projected sliced bread falling from N1,750 to N800 and a 50kg bag of rice from N55,000 to N27,500, with maize, yam, plantain, chicken, eggs and garri similarly halved. The dollar equivalents used the existing exchange rate, not the proposed one.
No timeline or operational monetary framework was provided. Segun Showunmi called it a confusion of political aspiration with economic feasibility. His cement example was telling: a $10 bag would cost N5,000 at N500/$, not N2,000.
The question is fair rather than frivolous, because Nigeria’s external position is the strongest in nearly two decades. Nigeria’s reserves reached $55.26 billion on 30 October 2026, up from $45.57 billion in January.
The current-account surplus hit $7.54 billion in the second quarter, while refined petroleum imports plunged 87.5 per cent, from $2.48 billion to $310 million, as domestic refining expanded. Inflation has declined for three consecutive months to 14.63%, and the Central Bank cut its policy rate by 350 basis points to 23% in September. With these improving fundamentals, why does the naira still trade at about ₦1,347 to the dollar?
Honesty requires one further point in the target’s favour. By purchasing power parity, the Naira is undervalued on a scale that makes ₦500 look conservative. The IMF’s implied PPP conversion rate for Nigeria is approximately ₦218 per international dollar for 2026, although later projections approach ₦320.
These are not market-rate forecasts. The gap between PPP and market exchange rates in poorer countries is partly structural, reflecting lower prices for non-traded goods and services, as explained by the Balassa-Samuelson hypothesis: the gap closes as productivity rises, not as politicians announce that it should.
The question, therefore, is not simply where the Naira should trade, but what productivity, export capacity and structural transformation would make a stronger currency economically sustainable
African currencies can also appreciate sharply. Ghana’s cedi strengthened approximately 36% against the dollar in 2025, reversing its position among the world’s worst-performing currencies in 2022. Gold exports, recovering cocoa receipts, an IMF-supported reform programme, falling inflation and rising reserves drove the turnaround.
But appreciation carries costs. The IMF warned that the stronger cedi was eroding non-extractive export competitiveness, while cocoa farmers faced falling international prices, delayed payments and farmgate pricing that made Ghanaian beans increasingly uncompetitive. Currency strength, it turns out, is not an unqualified economic victory.
Now the arithmetic the manifesto has not done. Nigeria’s broad money supply reached N146.60 trillion in September 2026, growing 24.47% year-on-year against a CBN target of 8%. At $55.26 billion in reserves, a hypothetical full dollar backing would imply N2,653 to the dollar.
Maintaining such backing at N500 would require $293.20 billion, a shortfall of $237.94 billion, equivalent to 61.5% of annual GDP. Apply the more generous currency-board test: the N41.59 trillion monetary base would require $83.18 billion in reserves at N500. Nigeria remains approximately $27.9 billion short. The man who sets the price of his yams by shouting across the market has not sold them; he has only disturbed the traders.
There is a denominator problem that reserve accumulation alone cannot fix. Currency in circulation has risen 81% in three years from N3.01 trillion in August 2023 to N5.44 trillion in August 2026. Reserves grew 20.4% in nine months; broad money grew 24.47% over twelve months. A currency’s external value is a ratio, and Nigeria has literally worked on the numerator while the denominator ran away.
The claim that halving the rate halves prices fails separately. Agriculture generated N11.87 trillion in nominal value added in Q1 2026, yet Nigeria spent N3.30 trillion importing food and beverages in the first half. Despite its agricultural scale, the country remains substantially dependent on foreign food supplies.
Yam is not priced in dollars. What the dollar touches is the diesel in the truck, the fertiliser, the generator at the mill and the packaging. That pass-through is real but it is a fraction of retail price, and it is asymmetric: Nigerian prices climb promptly when the Naira falls and descend reluctantly when it rises.
History is the most useful teacher, because Nigeria has run this experiment. The CBN held the naira at approximately N197 to the dollar for 16 months from February 2015. Reserves fell from $42.8 billion in January 2014 to $23.8 billion by September 2016, despite substantial foreign-exchange interventions.
The peg created a parallel market in which access to official dollars became one of the economy’s most valuable privileges. When the CBN abandoned the arrangement in June 2016, the official rate moved towards N305. The experiment with multiple exchange windows continued for years. When the markets were unified in June 2023, the official rate moved from about N472 to N753 by month-end and reached N912 by December.
The naira’s subsequent collapse reflected years of accumulated exchange-rate distortions and unresolved foreign-exchange shortages. The theory is not obscure. Mundell and Fleming’s impossible trinity, also known as the trilemma in international macroeconomics, holds that a country may have a fixed exchange rate, free capital movement and an independent monetary policy, but never all three.
The platform wants N500, wants foreign investment to finance security, electricity and roads, and implicitly wants lower interest rates to revive manufacturing. Pick two. In Nigeria it is always the rate that breaks.
Consider who pays if the target was achieved. The 2026 budget is benchmarked at N1,400 to the dollar. At N500, every dollar of oil revenue yields N500 instead of N1,400, a 64% loss on the Naira value of the largest federally distributable revenue source, in a budget already funding only 53.9% of its N68.32 trillion ($50.7 billion) from projected revenue of N36.87 trillion. Every state allocation would collapse.
Remittances of $21.81 billion in 2025 would lose 63% of their Naira value, so the family in Enugu receiving $200 a month would go from N269,000 to N100,000. Non-oil exporters would be crushed between dollar revenues and Naira costs, as Ghana’s cocoa farmers were. He who earns in one currency and eats in another should count twice before praying for either to change.
What would actually move the Naira is already partly under way, undramatically. The collapse in refined petroleum product imports, from $2.48 billion in the fourth quarter of 2025 to just $310 million in the first quarter of 2026, represents a quarterly reduction of $2.17 billion.
If sustained, that translates into an annualised foreign-exchange saving of approximately $8.7 billion in avoided foreign exchange demand, the most powerful Naira-positive development of the decade. Gas exports, non-oil export growth and continued import substitution are the real levers; on the money side the lever is restraint.
A money stock growing at 8 rather than 24.47%, alongside reserves expanding at 20% annually, could strengthen the naira substantially, potentially bringing the exchange rate to between N900 and N1,000 by 2031. That is not N500, but it is a 30% appreciation delivered by production rather than proclamation, and it would survive contact with a market.
Firstly, any candidate serious about the exchange rate should publish the money supply path that accompanies the target, because a rate without a monetary programme is a wish.
Secondly, the target should be stated in real rather than nominal terms.
Thirdly, the price list should be withdrawn and replaced with import-content estimates, because claiming yam and garri halve when the dollar halves invites dismissal of the sound parts of the programme.
Fourthly, the platform should say which leg of the impossible trinity it will surrender.
Fifthly, it should name the losers and say how they will be compensated.
Sixthly, the emphasis should move from the rate to what determines it: refining capacity, gas monetisation, non-oil exports, the security situation that keeps farmland idle, and the electricity that would let a Nigerian factory compete with a Chinese one. A full purse in an empty barn only means the hungry man can afford to buy from a stranger.
The most generous reading of N500 is that it describes where the Naira ought to be in over-a-decade well-run Nigeria, and on that reading it is not wrong. The objection is that a number offered without a mechanism, a timeline, a money supply path or an account of who pays is a campaign artefact rather than a policy, and Nigerians have paid for those before, to the tune of $11.7 billion defending the naira in 2016, yet depreciation more than doubled.
The only Naira that stays at N500 is one the country has earned. Emeka Nwosu can tell you the current rate to two decimal places. What he would like, and what no manifesto has yet offered him, is a reason to stop checking.
Akinola Morakinyo (Ph. D) writes on MINT economies from the Department of Economics, Finance & Quantitative Analysis, Kennesaw State University, GA, USA.