 Follow Us on Google Discover
Nigeria has an investment challenge that cannot be tackled by rhetoric. OPEC’s data showed Africa’s top crude producer pumped at its highest monthly level of the year in August, at 1.67 million bpd, though that remains well short of the government’s 2030 target of 3 million bpd.
It is not the difficulty of geology. The country’s upstream regulator estimates that the country has proven oil and condensate reserves of 37 billion barrels and gas of 215 trillion cubic feet. The capital, security and execution are.
The gap is evident in gas. In May, production was at 7.93 billion cubic feet per day, with 7 per cent of the output being flared and the flaring rate increased to 7.48 per cent in August.
The state planners have set 10 billion cubic feet per day as their goal by 2027, and the regulator claims there is still over 55 trillion cubic feet of “uncommitted reserves. They require ongoing, massive investment, which states can’t provide.
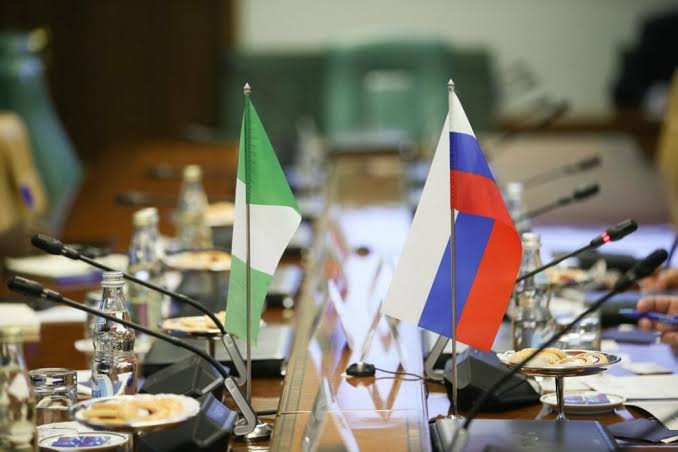
Therefore, when the Russians roll out the red carpet for energy firms, it is a good instinct to listen. The more difficult question is what must happen after they listen. As Africa Energy Week convenes in South Africa this month, Nigerian policymakers should ask not whether Russian partnerships bring money, but whether they leave the country stronger once it is spent.
What Russia offers
The time and reasons for engagement are very real. Russian companies have money, a long track record of engineering and a willingness to do business in markets that some Western majors will not go into. Lukoil has held an 18% interest in OML-140 offshore license for some time along with other partners, and has talked to Nigeria about more extensive cooperation in exploration, production, and refining. There is also competition among investors, which further adds to the improvement of terms. A country with Nigeria’s needs cannot afford to be sentimental about who funds its wells and pipelines.
What has changed
But the risks are not the same as those that pre-date the invasion of Ukraine. Lukoil and Rosneft were added to the US Treasury’s Russia sanctions list in October 2025 and come on the heels of previous sanctions targeting Russia’s oil production, shipping, financial institutions and energy technologies. In January, Reuters reported that Lukoil was in talks to sell its overseas stakes, including in Africa.
The question for Nigeria is not whether or not a deal is technically allowed, but rather whether or not it is genuinely wanted. Sanctions can reach the banks that process payments, the insurers that cover rigs and cargoes, the shippers that move product and the suppliers that service equipment. Even the best-laid plans can go astray when an ecosystem retreats. Ownership uncertainty may be added, too: a partner selling its international portfolio is not thinking 20 years ahead; so are reports that Lukoil intends to exit Ghana.
Lessons from elsewhere
Terms matter more than headline figures. In the Republic of Congo, Russia signed a joint venture agreement for a fuel pipeline between Pointe-Noire and Brazzaville with 90 per cent being provided by the Russian company, which will also provide the financing, equipment, personnel and fuel. That can provide infrastructure quickly. It also focuses ownership, supply and knowledge in one foreign hand.
The other side is in Libya. Russian fuel was significant for its supply, but this year it turned its attention to Western traders and was quick to reduce Russian imports, Reuters reported. Addiction can be overcome, but much more economical to prevent in the beginning.
Measuring success properly
Typically, the measure used is the size of the cheque. This is not the correct test. Nigeria’s refining industry is a case in point. A private initiative in Nigeria which costs about $20 billion, the Dangote refinery says it reached its 650,000 barrel-a-day capacity in February without needing foreign capital. It also shows the importance of supporting systems: a lack of local crude has been a problem for the plant. It’s quite a difference from what it was before. For years, Nigeria imported almost all fuel, with the state-owned refinery facilities at Warri, Kaduna and Port Harcourt having a combined nameplate capacity of only 295,000 bpd.
This is a second indicator: local content. The Nigerian Content Development and Monitoring Board states that the participation of Nigerians in Nigeria increased from less than 5 per cent before the enactment of the 2010 Act to 61 per cent in Nigeria; the target is to achieve 70 per cent participation in Nigeria by 2027.
These are the board’s numbers; the joint industry capacity audit is planned for the third quarter of 2026 to test them. Those who back the policy believe it prevents about $8 billion per year from being spent outside the economy, an amount that would be worth verifying separately. At the same board’s meeting on expatriates’ quotas, it was observed that technical skills were still being filled from abroad and a drive was launched to train more than 10,000 Nigerians.
Each and every partnership—Russian and otherwise—should be subjected to questions such as these:
- What is the number of Nigerian jobs created, skilled and managerial?
- Are the Nigerian suppliers getting much bigger contracts and getting to be bigger?
- Does it contain training and technology transfer (with measurable goals)?
- What is the total amount of state taxes and royalties received from the project over its lifetime?
Does it boost domestic fabrication, maintenance and petrochemical capacity?
Terms worth insisting on
Start with sanctions diligence: assess exposure across financing, insurance, shipping and technology, with clear remedies if a counterparty becomes restricted. Require change-of-control clauses so ownership cannot pass to an unknown buyer without consent.
No single foreign company or country should control a critical pipeline, refinery or gas hub without open competition and independent oversight. Equity structures should give Nigerian entities real stakes and decision rights, and debt secured against future output deserves special scrutiny. Publish key terms, or submit them to legislative review. Deals that cannot survive scrutiny are the ones most likely to cause trouble.
A forward-looking choice
This is not the time to close the door. Nigeria will require Russian, Western, Asian, Gulf and African capital and can’t afford to lose sight of all of them; otherwise, there is leverage to be leveraged.
The strongest energy sectors are not the ones that are getting the most investment, but the ones that are retaining as much value as possible at home and have the ability to change partners. Russian companies that do comply with those requirements should be welcome. Such ones should be politely informed, clearly and most of all, that Nigeria’s energy future is not for sale, on any terms.
Dipo Oladehinde is a skilled energy analyst with experience across Nigeria’s energy sector, plus knowledge of the country’s macroeconomy. He combines market intelligence, financial analysis and industry insight with micro- and macro-level analysis of local and international issues and offers technical input for policy-making and private-sector decisions.