 Follow Us on Google Discover
Nigeria’s decision to reduce its Monetary Policy Rate (MPR) from 26.5 per cent to 23 per cent represents a significant shift in the country’s monetary policy direction, with important implications for businesses, investors and the wider economy.
While the reduction does not automatically translate into cheaper loans or immediate economic relief, it presents an opportunity for businesses to reassess their financial strategies, restructure existing obligations, improve investment decisions and position themselves for sustainable growth.
For businesses operating in an economy where access to affordable capital has remained a major challenge, the reduction offers a reason for cautious optimism. The real significance of this policy adjustment, however, will depend on how effectively financial institutions transmit the lower benchmark rate to borrowers and how strategically businesses respond to the changing economic environment.
The MPR, set by the Central Bank of Nigeria, serves as a benchmark for interest rates and influences the cost of borrowing, the return on savings, investment decisions and the general level of economic activity. A reduction of 3.5 percentage points signals a move towards easing monetary conditions. In principle, lower policy rates can encourage lending, stimulate private-sector investment and support consumption. In practice, the impact will depend on other factors, including inflation, exchange-rate stability, banks’ risk assessments, liquidity conditions and the overall cost of doing business.
Also Read
For Nigerian businesses, therefore, the question is not simply whether interest rates have declined, but how this development can be converted into measurable commercial advantage.
A Window for Business Expansion
One of the most immediate opportunities created by a lower MPR is the prospect of improved access to financing. Businesses that previously postponed expansion plans because of expensive credit may find it worthwhile to revisit those decisions. Manufacturers could consider upgrading equipment, retailers could expand distribution, agricultural enterprises could invest in processing and storage, while technology companies could increase investment in infrastructure and product development.
For small and medium-sized enterprises, which form a substantial part of Nigeria’s commercial landscape, access to affordable financing can determine whether a business remains at its current scale or expands into new markets. Where lending rates decline, businesses may be able to finance working capital, acquire productive assets and undertake projects that were previously commercially unattractive.
However, lower MPR does not mean that commercial banks must reduce their lending rates by the same margin. Banks still consider credit risk, operating costs, collateral, repayment capacity and the prevailing economic environment. Business owners must therefore approach lenders with clear expansion plans, credible financial statements, realistic cash-flow projections and demonstrable repayment capacity.
The strongest candidates for financing will be businesses that can show how borrowed funds will generate revenue, improve productivity or reduce operating costs. Expansion should be driven by evidence of demand and a clear path to profitability, not merely by the expectation that credit will become cheaper.
Debt Restructuring and Improved Cash Flow
Another important opportunity lies in debt management. Businesses carrying expensive loans may use the changing interest-rate environment to initiate discussions with their lenders about restructuring existing obligations, refinancing eligible facilities or negotiating more favourable repayment terms.
High borrowing costs can place considerable pressure on business cash flow, leaving fewer resources for salaries, inventory, logistics, marketing and operational improvements. If lenders respond to the reduction in the MPR by lowering rates on eligible facilities, some businesses could reduce their financing burden and redirect the resulting savings towards productive activities.
Debt restructuring, however, requires careful analysis. A lower monthly repayment does not necessarily mean a cheaper loan if the repayment period is extended or additional fees are introduced. Businesses must compare the total cost of the existing facility with that of the proposed arrangement, taking account of interest, fees, penalties and the remaining repayment period.
Companies should also distinguish between productive debt and debt accumulated to cover persistent operating losses. Refinancing can improve the management of a viable business, but it cannot permanently correct weak revenue, excessive overheads or an unsustainable business model. The objective must be to create a healthier balance between debt obligations, operating income and long-term financial stability.
For chief executives, finance directors and business owners, this is an appropriate time to review loan portfolios, identify high-cost facilities and engage financial institutions with a well-supported refinancing proposal.
Investment, Production and Market Confidence
The reduction in the MPR also has implications for investment decisions. Interest rates influence how investors allocate capital between fixed-income instruments, equities, property, private businesses and other assets. When returns on interest-sensitive instruments begin to decline, some investors may become more willing to explore opportunities in productive enterprises, provided the expected returns justify the risks involved.
For Nigerian businesses, this creates an opportunity to strengthen investor relations, attract strategic partners and develop investment propositions that demonstrate credible returns. Companies seeking equity investment or long-term financing must be prepared to present transparent financial records, sound governance structures, realistic growth projections and clear business models.
The real estate sector offers a useful illustration. Property development requires substantial capital, while developers and prospective homeowners are affected by financing costs, construction expenses and purchasing power. If the reduction eventually translates into more affordable mortgage and development financing, it could support housing demand, improve project feasibility and encourage investment in residential and commercial property.
Nevertheless, the relationship between interest rates and property market growth is not automatic. Land costs, building materials, infrastructure deficits, inflation and household incomes remain important determinants of affordability. Developers must therefore align new projects with genuine market demand and realistic payment structures rather than rely solely on expectations of cheaper financing.
Manufacturing, agriculture, transportation, construction and technology could also benefit if financing conditions improve. Lower financing costs can support equipment acquisition, inventory management, supply-chain efficiency and business innovation. These sectors can, in turn, contribute to employment creation, stronger domestic production and broader economic activity.
The Importance of Monetary Policy Transmission
Despite these opportunities, it is important to distinguish a reduction in the MPR from an actual reduction in commercial lending rates. The Central Bank of Nigeria announced the adjustment at its September 21–22, 2026 Monetary Policy Committee meeting, describing it as a recalibration intended to improve the transmission of monetary policy. The CBN also retained the cash reserve requirement for deposit money banks at 45 per cent. The CBN’s official monetary policy decisions provide the details of the adjustment.
The distinction matters because businesses cannot benefit fully from a lower benchmark if banks continue to charge high lending rates. Following the announcement, concerns were raised about the persistence of commercial borrowing costs, with manufacturers warning that lending rates around 30 per cent could limit the practical benefit of the reduction. Reporting on manufacturers’ concerns illustrates the gap between a policy adjustment and the relief businesses actually experience.
For this reason, the success of the rate adjustment must be assessed not only by the size of the reduction but also by its effect on lending conditions, investment, production and employment. Banks must evaluate how improved market conditions can translate into more competitive financing, while businesses must strengthen their creditworthiness and demonstrate responsible use of borrowed funds.
Policymakers, in turn, must continue to address inflation, exchange-rate pressures and liquidity management. A reduction in interest rates that is not supported by durable macroeconomic stability could create renewed pressure on prices and undermine the gains businesses are seeking to achieve.
Strategic Priorities for Business Leaders
Business leaders should respond to the changing environment with deliberate financial and operational decisions. The immediate priority is to review existing borrowing arrangements and engage lenders where refinancing opportunities are commercially viable. At the same time, businesses should reassess expansion plans, identify investments capable of generating measurable returns and strengthen cash-flow management.
Companies must also avoid the temptation to increase borrowing simply because monetary conditions appear to be improving. Debt remains a financial obligation, and every new facility must be supported by realistic revenue projections and a clear repayment strategy. Where internal funds are sufficient, businesses should compare the cost of borrowing with the potential benefits of financing expansion through retained earnings or strategic partnerships.
Equally important is the need to improve productivity. Access to financing creates limited value when businesses continue to suffer from inefficient operations, poor inventory control, weak customer retention or inadequate market research. The most resilient companies will combine prudent financial management with innovation, customer-focused marketing, effective leadership and disciplined execution.
For small businesses, maintaining accurate financial records, separating personal and business finances, formalising operations and building reliable banking relationships can improve access to future credit. For larger organisations, treasury management, capital allocation and periodic debt reviews should remain central to corporate strategy.
From Policy Adjustment to Economic Growth
Ultimately, the reduction in Nigeria’s MPR from 26.5 per cent to 23 per cent presents an opportunity, but its long-term value will depend on what follows. A more favourable financing environment can encourage investment, support business expansion, improve debt management and stimulate economic activity. However, these benefits must be reinforced by stable prices, predictable economic policies, efficient financial intermediation and stronger domestic production.
Government also has a role to play by improving infrastructure, reducing avoidable regulatory burdens, supporting small businesses and ensuring that fiscal policies complement the pursuit of monetary and economic stability. The private sector, meanwhile, must demonstrate that access to capital can translate into productive investment, sustainable employment and measurable value creation.
Nigeria’s businesses should therefore view this development neither as a guarantee of cheaper money nor as a reason to delay strategic decisions. It is an opportunity to review financial structures, strengthen business models and prepare for a potentially more supportive investment environment.
The ultimate measure of success will not be the movement of the benchmark rate alone. It will be whether businesses can access capital at more sustainable costs, produce more efficiently, expand responsibly, employ more Nigerians and compete more effectively in domestic and international markets.
For Nigeria to achieve meaningful economic expansion, monetary policy must move beyond numerical adjustments to deliver tangible improvements in the real economy. Businesses must be ready to seize the opportunities that emerge, while financial institutions and policymakers must ensure that the benefits of improved conditions reach the productive sectors that drive growth.
The reduction in the MPR is a signal for strategic preparation. The businesses that respond with sound financial discipline, purposeful investment and operational excellence will be better positioned to turn this policy development into sustainable growth.
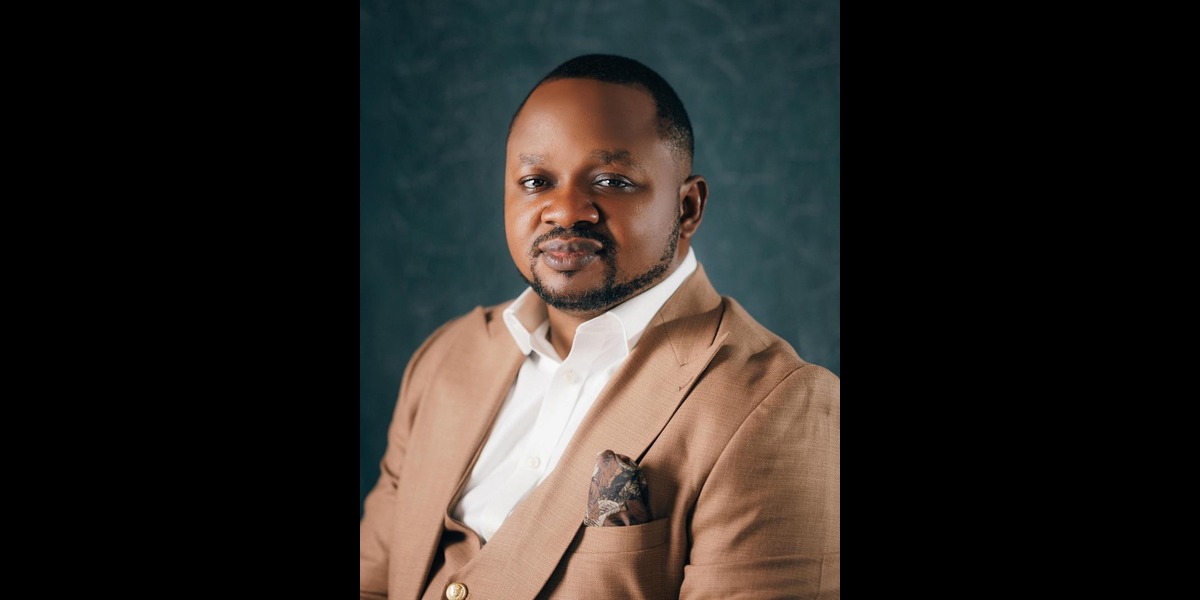
Dr. Oluwatosin Olatujoye is a business leader and real estate entrepreneur. He is the Group Chief Executive Officer of Zylus Group International, a well structures real estate company in Nigeria. Check www.zylushomes.com