 Follow Us on Google Discover
The financing pressures facing Nigerian businesses extend beyond access to loans.
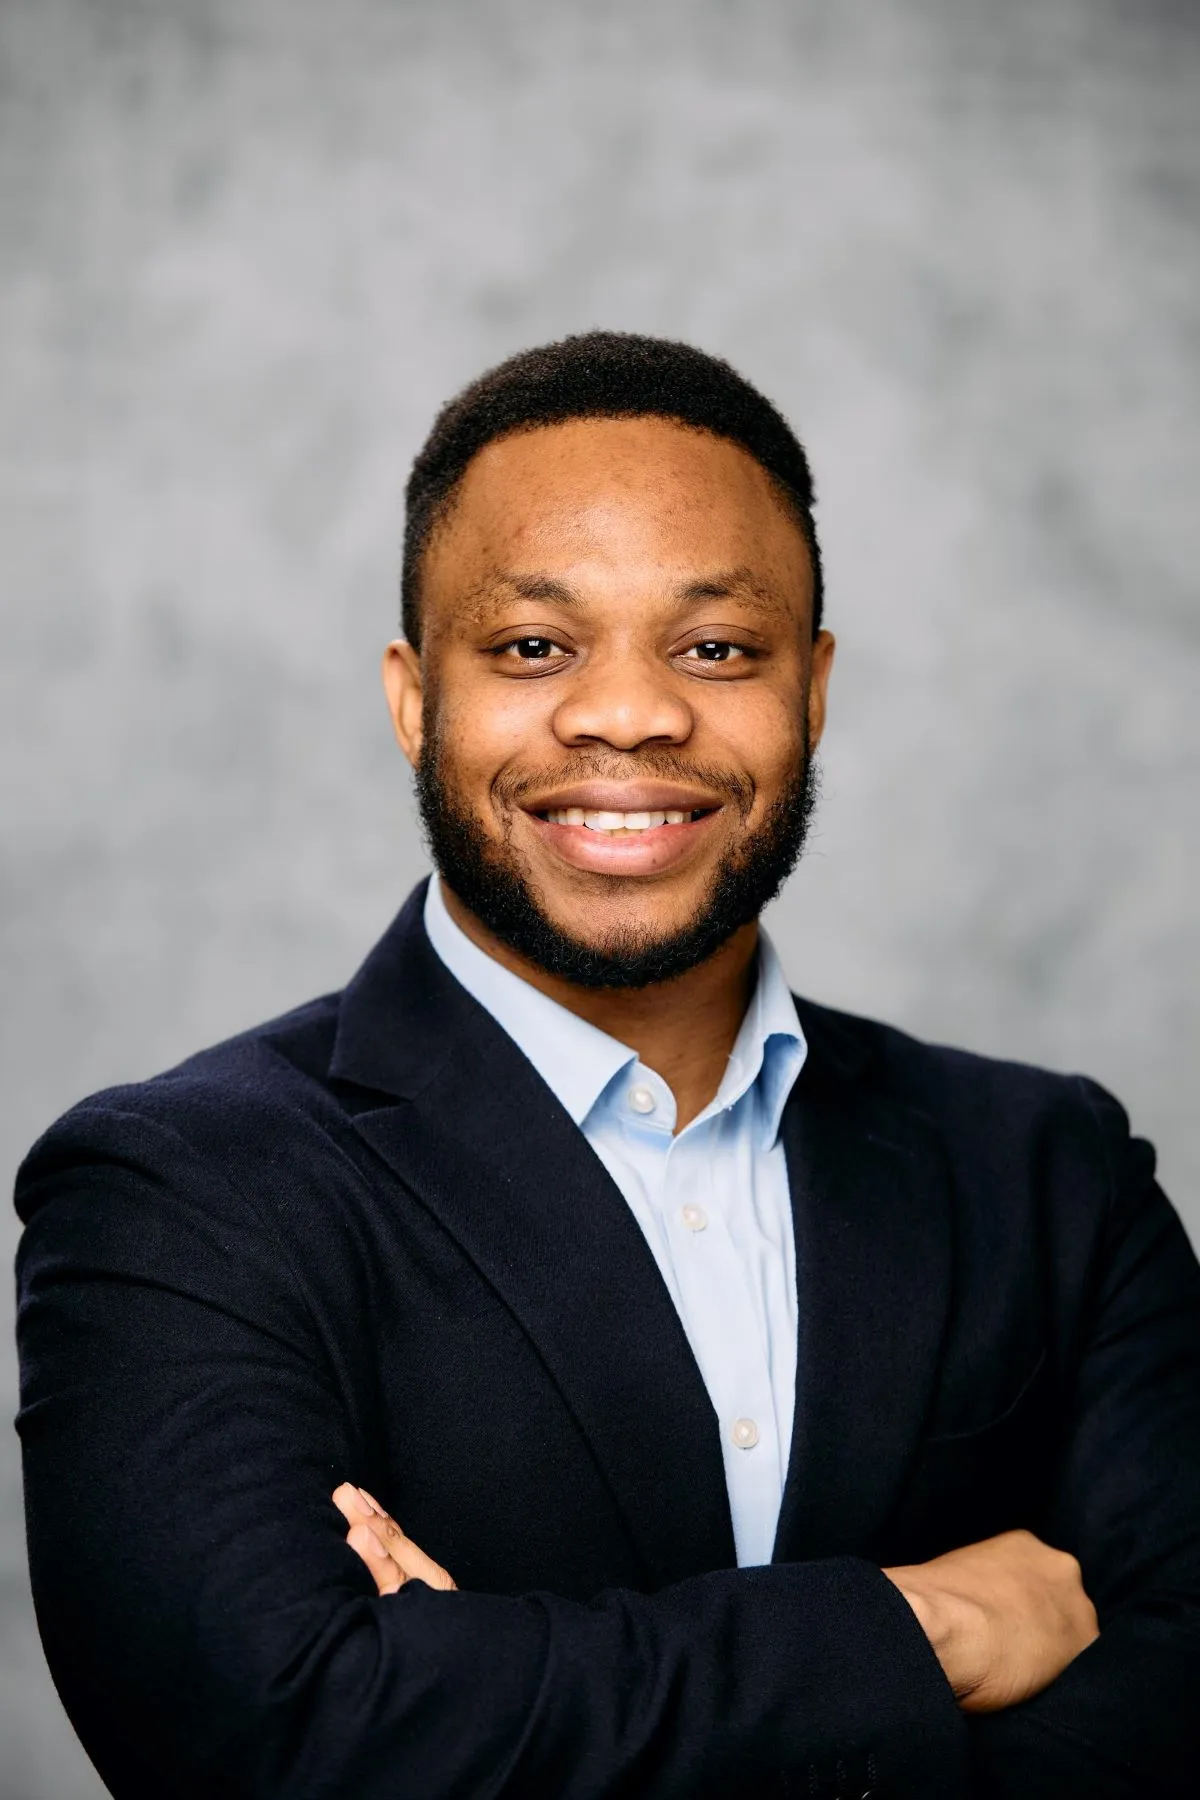
Delays and uncertainty in moving money across borders can increase the amount of capital a company needs to fulfil orders, maintain inventory and meet its obligations, according to fintech founder and product leader Kelvin Efosa Obasuyi.
Obasuyi, founder and CEO of Vector Innovation and a co-founder of business-financing company 56 Capital, believes payment infrastructure deserves greater attention in discussions about SME financing and international trade.
His assessment centres on a distinction that can be overlooked in those discussions: a business may have sufficient funds to undertake a transaction without being able to deploy them at the point they are needed.
Also Read
An importer may have paid for inventory while its overseas supplier is still awaiting cleared funds before releasing the goods. An exporter may have completed an order but remain unable to use the proceeds to finance its next production cycle. A company operating across currencies may hold balances in one account while facing an obligation it cannot immediately meet elsewhere.
Each situation can place pressure on working capital. For businesses with limited reserves, the response may involve additional borrowing, delayed purchases or a decision to decline another order.
Obasuyi’s perspective draws on experience assessing businesses seeking finance at 56 Capital, working on financial technology products at Duplo and building cross-border payments and treasury infrastructure at Vector. Across those roles, he has approached the same operating challenge from different directions: how businesses obtain capital, understand their financial position and move money to support commercial activity.
In his view, these functions need to be considered together. A financing facility can help a business purchase stock, but the timing of payment, delivery, sale and collection determines how long that facility must remain outstanding.
Where payment delays extend that cycle, the financing requirement can increase even when the underlying order remains profitable.
The cost is consequently broader than the transfer fee or exchange-rate quote. Businesses must also account for the time their money remains committed, the reserves they maintain against uncertainty and the opportunities they cannot pursue while waiting for funds to become available.
That does not mean every delayed payment results in a loan. The effect depends on the company’s cash position, contractual terms and operating model. However, a business with little financial headroom has fewer options when an expected settlement does not arrive.
Obasuyi’s understanding of these priorities developed during Vector’s early commercial work. He initially expected price and geographic coverage to be central to the company’s appeal. Customer conversations highlighted the importance of dependable settlement, transparency and responsiveness alongside cost.
The urgency behind a transfer often reflected a wider business commitment. A supplier might be waiting to release goods, a finance team might need to authorise another payment, or a company might be approaching a contractual deadline.
Those considerations shaped his view that payment providers should understand the commercial purpose of a transaction and give customers the information needed to plan around it.
The implications extend to businesses on both sides of an international trading relationship.
A British supplier selling to a Nigerian distributor needs a dependable basis for deciding when to release inventory, schedule production or extend payment terms. The Nigerian buyer needs to understand funding requirements, currency conversion and settlement timing before making commitments to its own customers.
Uncertainty can influence the terms on which those businesses trade. A supplier concerned about payment timing may require funds earlier. A buyer may hold additional reserves or initiate transfers further in advance. These arrangements can protect individual counterparties while increasing the amount of capital committed across the relationship.
For Obasuyi, this makes cross-border payment performance relevant to British exporters, African importers and the financial institutions supporting them. The commercial objective is to give each participant a clearer basis for fulfilling its obligations.
That international perspective also informs his approach to developing Vector from the UK. His work involves bringing together the operating requirements of businesses trading across African and international markets with the expectations of banking, payment and liquidity partners.
The challenge requires an understanding of both sides. Business customers need timely execution and clear information. Financial institutions need appropriate customer checks, transaction information, controls and records. A service intended to support international trade must accommodate those requirements throughout the payment process.
Obasuyi’s product experience at Duplo reinforced the importance of organising financial information around decisions. His reporting and analytics work covered areas including payment activity, approvals, settlement performance, wallet balances and spending.
The value of that information lay in helping business owners and administrators identify where money or a process was constrained, and what required attention.
He applies a similar perspective to Vector. Access to payment providers becomes more useful when businesses can also understand their available balances, outstanding commitments, funding requirements and settlement position.
Without that visibility, a company may respond cautiously by keeping more cash idle or spreading balances across several providers. Those precautions may be reasonable, but they can leave less money available for stock, salaries or expansion.
The wider industry continues to face a gap between infrastructure development and improvements experienced by customers. The Financial Stability Board’s October 2025 review found only modest progress in global cross-border payment indicators since 2023, despite substantial policy work.
Obasuyi’s assessment is that providers should therefore examine outcomes beyond transaction volume. Businesses need to know how long payments actually take, how much variation exists around expected settlement times and when beneficiaries can use the funds.
A fast average can conceal lengthy delays affecting some customers. Similarly, a transaction marked as completed within one platform may leave the customer uncertain about whether the beneficiary has received usable funds. Providers need to explain those distinctions clearly.
He also recognises that payment technology has limits. Businesses still require financing for expansion, equipment and contracts involving long customer payment terms. Liquidity availability, banking hours and regulatory checks can affect international settlement.
Responsible product design must account for these constraints. The opportunity is to make requirements clear early, reduce avoidable delays and provide accurate information when a transaction requires intervention.
For lenders, this means examining payment arrangements alongside a borrower’s operating cycle. For business owners, it means comparing providers on funding requirements, settlement consistency, transparency and support as well as price.
For UK and African institutions supporting international trade, it means recognising how payment arrangements affect the commercial relationship between buyer and supplier.
Obasuyi’s broader argument is that capital access and capital efficiency belong in the same discussion. Businesses need appropriate funding, alongside infrastructure that allows them to use it productively across markets.
For a company managing limited resources, the ability to put funds back to work with greater confidence can determine whether it fulfils its next order—and whether an international trading relationship has room to grow.
Kelvin Efosa Obasuyi is the founder and CEO of Vector Innovation and a co-founder of 56 Capital. A seasoned product leader and also holds an MBA from the University of Oxford.