 Follow Us on Google Discover
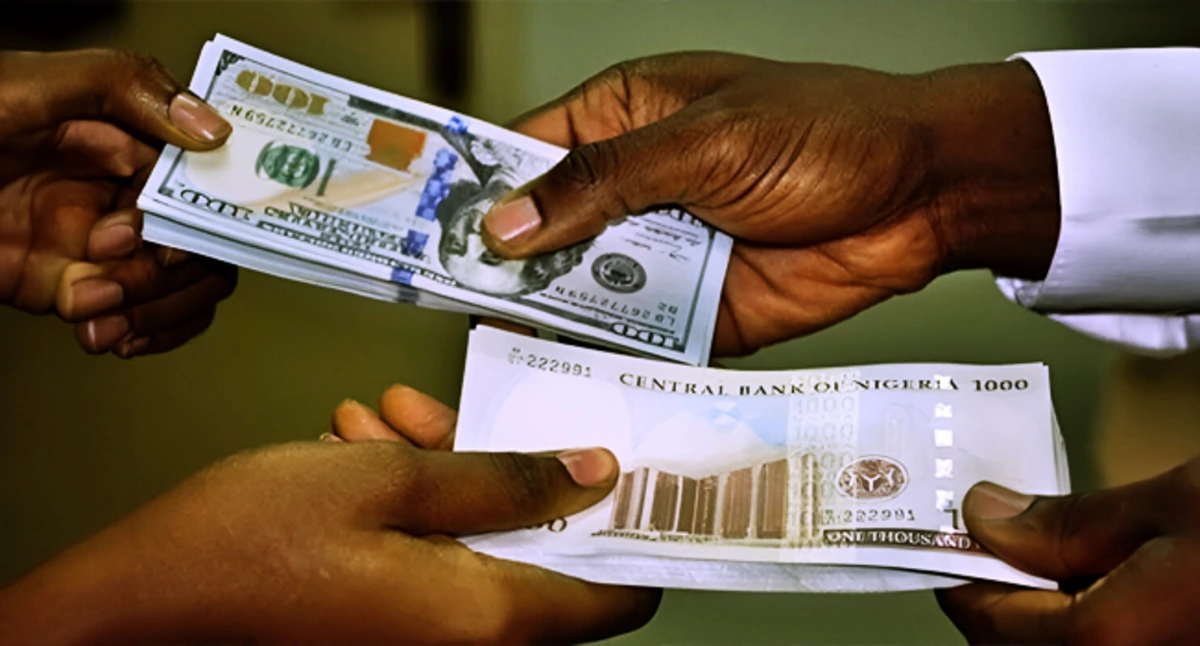
Latest fundamental analysis projects that the USD/NGN exchange rate will remain around N1,290–N1,370 per US dollar through October.
The Monetary Policy Committee’s (MPC) easing its policy stance, with the policy rate reduced to 23%, combined with seasonal fourth-quarter import demand, is likely to limit any sharp appreciation.
Compared with US Federal Reserve rates, the real interest-rate carry trade remains attractive to foreign portfolio investors despite recent monetary easing. Disinflationary trends, easing inflation, which is approaching 14%, and increased domestic petroleum-processing are supporting real-yield sentiment and slowing the naira’s domestic depreciation.
However, relatively low interest rates in Nigeria means that foreign and domestic investors have less of a spread to earn, thus lowering capital inflows (or raising outflows) seeking high risk-adjusted returns. This has a natural insulating effect on demand for domestic currency.
Also Read
Higher foreign exchange demand from corporates and consumers is expected ahead of the Yuletide season and will likely keep the naira supported around the N1,300/$ level.
The fourth quarter is typically characterized by an acceleration of commercial and consumer activity in many economies (restocking of inventories, holiday shopping, agricultural or manufacturing input buying), creating demand for foreign currency to pay for imports.
Consequently, the naira is expected to follow a range-bound path with gradual depreciation. Foreign reserves remain comfortable at more than US$55 billion, providing the Central Bank of Nigeria (CBN) with substantial capacity to intervene in the event of a sharp exchange-rate correction.
FX reserves are strong enough to back the Naira heavily, however there are opposing forces in the market that prevent the Naira from appreciating heavily beyond 1,290/$: The CBN doesn’t focus on using the record reserves to seek profits from a stronger exchange rate, but instead to ensure price discovery, maintain liquidity in the NAFEM, and ensure reserve longevity.
Operational reforms designed to improve price discovery have narrowed the gap between the official NFEM rate and the parallel market rate, reducing arbitrage, including roundtripping.
Liquidity and trading volumes in the official market have improved, supported by sustained high crude oil production, which is at multi-year highs, and elevated international oil prices.
US dollar retreats from monthly highs
The DXY (US Dollar Index) is currently trading around 101.80, retreating from multi-month highs near 102.9. After a bullish rally over several weeks, the US Dollar Index lost momentum amid volatility in the technology sector and declining Treasury yields.
US inflation figures again exceeded expectations, with annual CPI at 3.7% and PPI increasing by 6.3% year over year. These figures have renewed debate about the prospect of interest rates remaining elevated for an extended period.
Markets are pricing in an 84% probability that the FOMC will leave interest rates unchanged at its October 27-28 meeting, while expectations remain tilted toward a possible final 25-basis-point increase in December.
Federal Reserve Chair Kevin Warsh highlighted that hotter-than-expected inflation data had not yet materially altered his assessment of the US economy. He offered no direct forward guidance as he entered the Federal Reserve’s pre-meeting blackout period.
A decline in equities reflected concerns about artificial-intelligence capital expenditure and credit stress in technology infrastructure. Investors sought safety in the greenback, while the US 10-year Treasury yield fell to 5.07%-5.09%. Lower yields reduce near-term demand for the US dollar.
Large technology companies and hyperscalers are raising billions of dollars in debt to finance the expansion of their artificial-intelligence data-centre platforms, power-grid upgrades, and hardware. The resulting increase in debt issuance has widened corporate-bond spreads and raised credit yields, prompting investor concerns about debt levels, slow amortization, and credit stress in the technology sector.
Flight to Quality (Demand for Treasuries): When US equity markets decline because of technology earnings or macroeconomic concerns, investors often favor safe-haven US Treasury securities. Increased demand for these bonds drives their prices higher and yields lower.