 Follow Us on Google Discover
Nigeria’s headline inflation fell to 14.63% in September 2026, down from 15.39% in August and 20.98% in September 2025, according to the National Bureau of Statistics (NBS, 15 October 2026).
That is a drop of 0.76 percentage points in one month and 6.35 points in a year. It is the fourth straight monthly decline.
The headline is good news.
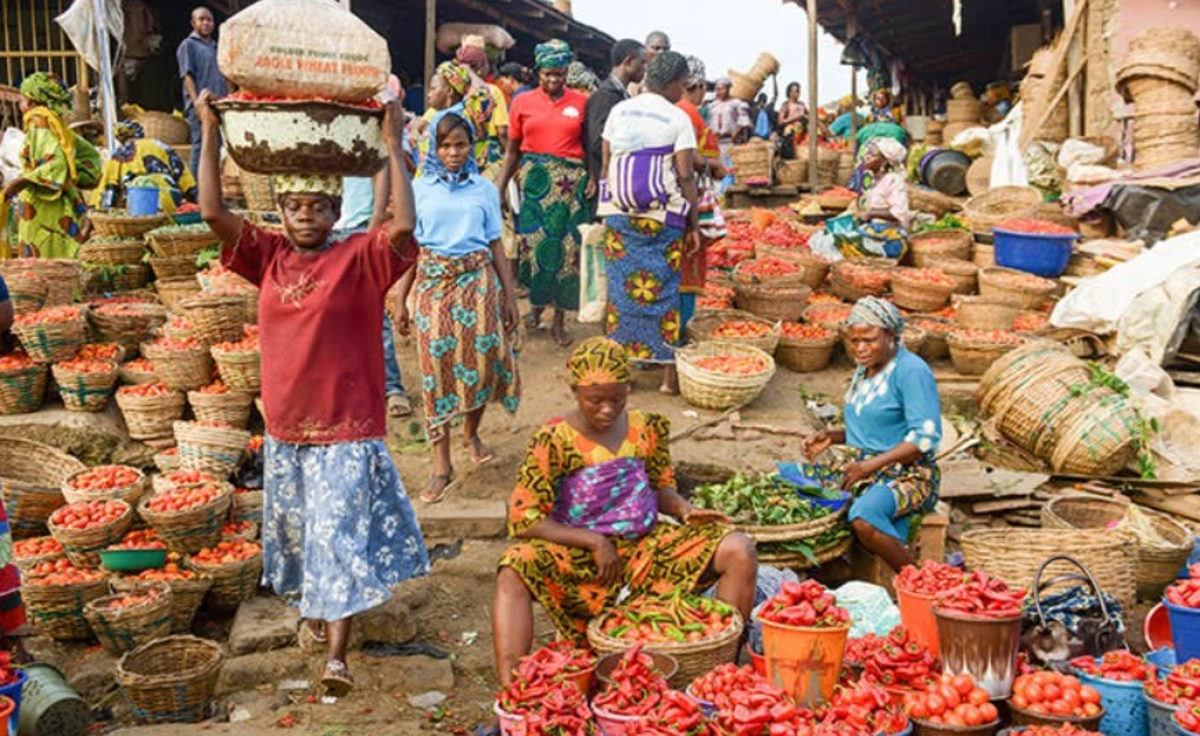
September fall came entirely from food prices dropping during the harvest. The prices that do not depend on the harvest went up faster.
What fell?
Food. On a month-on-month basis, food prices fell 1.55% in September, after rising 1.02% in August. The NBS named grains, rice, eggs, onions, palm oil, vegetables, potatoes, plantain and tomatoes. Month-on-month means the change from one month to the next, without comparison to the previous year. A negative number means prices fell.
The rural figures tell the same story. Rural prices fell 0.89% month-on-month in September. Urban prices rose 0.53%. Farmers sell at harvest, and villagers feel the price drop first. Cities pay for transport, rent, power and services, and those costs did not fall.
So, month-on-month inflation came in at just 0.06%. Multiply that pace across twelve months and you get an annual rate of less than 1%. Nobody should expect that to continue. Harvest prices fall every year around this time and climb again in the lean season.
What went up?
Core inflation. Core strips out farm produce and energy, the two most volatile parts of the basket. It is the best guide to underlying price pressure: rents, school fees, transport fares and manufactured goods all rose. Core rose 1.11% month-on-month in September, after a fall of 0.06% in August.
Do the arithmetic. A 1.11% monthly rise, compounded over twelve months, is 1.0111 raised to the twelfth power, or about 1.142. That is an annualized pace of 14.2%. The published annual core rate is 12.95%. In September, then, the underlying pace ran above the annual figure. One month does not make a trend. It does tell you that the September headline flatters the picture.
Food inflation on an annual basis is still 19.59%, little changed from 19.57% in August (Reuters, 15 October 2026). A Nigerian household that spends half its income on food is facing prices 20% higher than a year ago.
Why does the energy line matter now?
Because petrol is expensive and oil is high. Brent crude traded above $100 a barrel in mid-October, and some Abuja filling stations raised pump prices to about N1,405–N1,409 per liter. NNPC’s N66-per-litre customer relief runs only until 31 October.
The World Bank’s October 2026 Nigeria Development Update puts it plainly. Inflation fell from 27.6% to 15.2% between January and December 2025, then “stalled” at around 15.5% in 2026, which the Bank says is more than double the rate of peer countries. Its headline reason is the energy shock. Fuel feeds into transport and transport feeds into the price of everything else. That is how energy prices end up in core inflation with a lag.
What does this mean for CBN?
The CBN cut the Monetary Policy Rate to 23% in September. Against September inflation, the real policy rate is 23 minus 14.63, or 8.37 percentage points. That is a wide cushion. On paper, it leaves room for another cut.
The market rate is the better test. At the 14 October Treasury bill auction, the 364-day stop rate was 15.90%. Subtract 14.63% and the real return on a one-year bill is 1.27 percentage points. Strip out the harvest effect and use the core pace of about 14.2%, and the cushion is still thin. Investors are accepting a small real return because they believe inflation will keep falling. If core keeps rising, that belief breaks, and yields will go back up whatever the CBN does with the MPR.
What does this mean for the Federal Government?
This is the harder part. Nigeria votes in January. The World Bank’s October 2026 Africa Economic Update raised its 2026 growth forecast for Nigeria to 4.3%, and in the same report warned that “rising pre-election spending ahead of the 2027 elections” is a downside risk. The IMF raised its 2026 forecast to 4.2% and has urged Nigeria to resist calls to restore blanket fuel subsidies.
The fiscal position did improve. The World Bank says net revenues rose to 4.2% of GDP, or ₦10.5 trillion, in the first half of 2026, helped by FX and petrol reforms and lower deductions from oil revenue. It also expects spending pressures to rise in the second half. Revenue raised through reform and then spent on campaign-season handouts puts money into the same markets where core prices are already rising.
Two things to do before the next print.
First, the CBN should hold at its next meeting. The real policy rate is wide, but one month of falling food prices is not evidence that underlying inflation is beaten. Cutting into a rising core number repeats the mistake of reading the harvest as policy success. A pause costs less than a reversal in Q1 2027.
Second, the Federal Government should publish a pre-election spending ceiling and keep the fuel market open. Establishing a spending cap, publishing that number in public, quarter by quarter, is the cheapest way to show investors that the revenue gains of 2026 will not leak away in December and January.
Blanket fuel subsidies would lower the pump price for a few months and push the cost onto the budget and the naira. The ₦66 relief ends on 31 October. Let it end and aim any support at transport for low-income workers rather than at every litre sold.
Watch the October core number.
October CPI will tell you whether September was a harvest month or a turning point. Watch core month-on-month. If it falls back below 1%, the disinflation is real and the CBN can ease again in 2027. If it stays above 1%, the 14.63% headline was a harvest discount.
Kalu A. Aja is a financial planner and author.
Follow me on X @FinPlanKaluAja1